The AI Growth Advantage:
How Growth-Ready Organizations Turn AI into Enterprise Value 

AI investments don’t guarantee growth. But our new research shows growth-ready organizations are significantly ahead in turning new technology into enterprise value. 

The AI Growth Advantage:
How Growth-Ready Organizations Turn AI into Enterprise Value

Based on input from circa 250 leaders across markets and industries, our 2026 Catalysts research looks at how high-growth companies organize around AI, compared to those growing at a moderate and low pace. High-growth organizations approach AI differently.

They are more likely to:

Connect AI to growth and innovation

Embed AI into business strategy and day-to-day operations

Invest broadly in workforce AI and human thinking capability

Create cultures where experimentation and learning are expected

How high-growth companies create clear organizational conditions for AI impact.

Our research points to three key findings about the next phase of AI transformation:

  1. What growth leaders are doing differently. High-growth organizations aren’t simply adopting more AI; they’re embracing and embedding it. 
  2. Organizing for the AI era. Sustained impact requires creating a reinforcing system across strategy, leadership, work, capabilities, governance, and culture. 
  3. Leadership is the AI multiplier. As AI becomes an enterprise-wide mandate, leadership becomes the next constraint. 

Download Report
The AI Growth Advantage: How Growth-Ready Organizations Turn AI into Enterprise Value

*Fill in all required fields

Thank you for your interest in Prophet’s research!

Get in touch with our team to learn how we help organizations move from experimentation to impact by aligning strategy, leadership, people, operating models and culture around their AI ambition. 

Contact us.

*Fill in all required fields

Thank you for your inquiry.

If your submission requires a response, we will be in touch shortly. In the meantime, we encourage you to learn more about our firm and read some of our latest and greatest thinking.

Our Team

Paul Teuton
Partner

Hailey Armstrong
Senior Engagement Manager

BLOG

Uncommon Intelligence: Welcome to the Age of AI Realism 

How leaders can close the gap between AI ambition and impact.

At Prophet’s latest Uncommon Intelligence event in Abu Dhabi, there was no shortage of optimism in the room. Bringing together CMOs and senior business leaders from across industries including government, healthcare, hospitality and banking, the discussion reflected genuine excitement about what AI could make possible.

But that optimism came with a dose of realism: AI’s promise is enormous, but realizing it is proving more complicated.

Leaders are under pressure to move faster, automate more and avoid being left behind. Yet beneath that urgency sit harder questions: Where is AI creating meaningful value? What is the ROI? And why, despite rapid experimentation and adoption, does its impact so often fall short of expectations?

These are not uniquely Middle Eastern challenges. They reflect a much broader issue facing leaders around the world. Closing the gap between AI’s potential and its real-world impact requires organizations to look beyond it as another productivity tool.

That means moving from efficiency to effectiveness and, ultimately, enhancement. There was broad agreement that creating average work faster isn’t the goal. 

1. Start with the Outcome, Not the Tool

Perhaps the biggest danger surrounding AI right now is starting in the wrong place.

With so many slick new tools, agents and use cases emerging almost daily, there is an understandable temptation to ask, “How can we use this?” A better question is: “What are we trying to achieve?”

Productivity gains alone don’t guarantee competitive advantage. Organizations need to identify where AI can create real value, with a clear line of sight to business impact and ROI.

That requires leaders to resist chasing every new platform. With new technology emerging constantly, the challenge is increasingly about selecting the right capabilities for the right problem. In other words: Impact first, tools second.

2. AI Transformation is About Leading From the Front

If AI is going to change how an organization creates value, it cannot simply be delegated to an innovation team or technology function. Leaders need to own the outcome.

That means establishing priorities, allocating resources, and modeling the behaviors they want others to adopt. AI adoption isn’t only a technology transformation; it changes workflows, roles and ways of working.

This is particularly apparent in marketing, where there is significant opportunity across efficiency, effectiveness and enhancement, but functional expertise remains critical. Not every activity should become AI-first. Some areas are better suited to AI-powered collaboration, while others still depend heavily on practical human knowledge.

The onus on leadership is to understand the difference and set the direction.

3. Keep Human Intelligence Firmly in the Equation

There was also a realistic and pragmatic view about AI’s limitations. It isn’t a silver bullet, and speed is not the only measure of success.

AI can process, analyze and create, at remarkable scale but people still bring the expertise, judgment, context and creativity that determine whether the output is useful. This is where the idea of augmented intelligence becomes important: not AI replacing human intelligence, but the two working together to produce better outcomes. This means thinking about human and artificial intelligence as part of one extended workforce, each bringing different strengths to the task.

The opportunity lies in finding the right balance. Where can AI meaningfully improve the work? Where does human intelligence matter most? And where can combining the two deliver something genuinely better?

4. Interrogate AI, Don’t Evangelize it

We bring this to life with AI twins, which can be used to gather insights, test ideas, and pressure-test decisions. Rather than simply demonstrating another AI capability, the aim was to provoke a different question: What would you ask your digital twin?

When grounded in the right data, digital twins can challenge existing assumptions, surfacing perspectives that are direct, unexpected, and sometimes uncomfortable.

That is part of their value. Leaders don’t need AI to tell them what they already think, they need it to help uncover blind spots, challenge assumptions and provide new perspectives that can lead to better decisions.

It points to a broader mindset shift. The goal shouldn’t be to evangelize AI or adopt technology for technology’s sake. It should be to interrogate it. Where can it help us see something we couldn’t see before? Where should we challenge its output? And where can human judgment and AI together lead to a better decision?


FINAL THOUGHTS

Leaders don’t need every answer before they begin. Waiting for the perfect technology stack or operating model can become a barrier in itself.

Start with a clear objective, bring human intelligence to the problem and choose the right tools for the task. Then try, learn and iterate.

The organizations that turn AI into growth won’t be those using the most tools, but those clearest about where it can create distinctive value and how to make that value stick.

Don’t just move faster. Make sure you’re moving somewhere worth going. Explore Prophet’s Augmented Intelligence approach

BLOG

CPG Companies Can’t Price Their Way to Growth Forever

How CPG leaders can move beyond short-term pricing levers to unlock uncommon growth.

In recent years, the consumer packaged goods (CPG) sector has relied heavily on price-led strategies to drive top-line revenue. From direct price hikes to smaller pack sizes and tighter promotions, companies have pulled multiple pricing levers to protect growth. While the numbers on the balance sheet showed double-digit growth, the underlying health of the sector told a different story: stalled volume growth and flat consumer penetration.

Now, that growth equation is reaching its limits.

We are entering the “Post-Price Era.” Consumers facing prolonged economic uncertainty are becoming more deliberate about what they buy, where they buy it, and which brands they are willing to pay more for. Familiarity and loyalty alone are no longer enough. Consumers are more willing to compare alternatives, switch brands, and trade down when the value equation does not add up.

For CPG leaders, this creates a more fundamental growth challenge. If price can no longer do the heavy lifting, where will the next wave of growth come from?

The answer is unlikely to come from a single lever. Leaders must simultaneously find new sources of demand, protect margins, accelerate meaningful innovation, and build brands that remain distinctive and relevant. At the same time, many are navigating fragmented customer attention, changing expectations and pressure to transform their organizations and harness AI.

The Opportunity: Reclaiming Demand-Led Growth

In an uncertain environment, the instinct is often to become more defensive: prioritize short-term returns, focus resources on the biggest brands and favor incremental improvements with a clearer path to payback. But protecting what works today is not the same as creating what will drive growth tomorrow.

Our new report, The CPG Growth Revolution, explores how CPG leaders can move from defending today’s performance to creating tomorrow’s demand. Different growth challenges require different moves:

  • Category growth has stalled: Identify emerging demand spaces and prioritize the moves with the greatest upside.
  • Own label is gaining ground: Strengthen brand and product architecture, sharpen positioning and uncover new brand and offer opportunities.
  • Strong brands aren’t breaking through: Modernize marketing strategy, refine routes to consumers and improve activation effectiveness.
  • Innovation is falling flat: Anticipate future consumer needs to shape innovation strategy and uncover new territories for growth.

The report provides a practical framework for action, covering:

  • What needs to change: Five shifts CPG leaders can make to redefine consumer value, create new sources of growth, and build the capabilities to deliver them.
  • How to make it happen: How to break down functional silos and connect brand, innovation, pricing and other growth levers around shared priorities.
  • Where to focus: A 360-degree uncommon growth model spanning business strategy, brand, marketing, innovation and experience.

Read the full CPG Growth Revolution report to discover how to build a more connected approach to demand-led growth.

Read the report.

FINAL THOUGHTS

Growth that matters starts with clarity. We are ready to help you find it.

If and of these priorities resonate with our challenges, let’s set up a conversation. Together, we’ll help you determine which lens is most relevant and craft a path forward.

BLOG

Future-Proofing Your Portfolio:  
Brand Architecture in the Age of Agentic Search

As agentic search demands semantic clarity over categorical keywords, brands must rethink portfolio architecture and naming to avoid being hidden behind walls of confusion.

With the rise of agentic search, conversational commerce, and autonomous shopping, marketing leaders are urgently working to optimize the new disintermediated customer journey. Brands are rapidly deploying tactics to rise in LLM rankings — restructuring digital properties, seeding third-party reviews, and managing community-created content to shape the “agent narrative.” 

Yet one of the most critical levers to influence AI recommendation engines remains entirely overlooked:
your portfolio structure and naming strategy. 

According to Gartner,  over 80% of marketing leaders are working to deploy tactics for machine legibility — from content to third-party reviews — fewer than 15% have audited their portfolio architecture or naming. 

Historically, portfolio architecture and naming have been used to drive offer clarity and telegraph value. At Prophet, our approach starts with helping clients build a taxonomy to clarify offer types. In your architecture, it’s critical to also represent the relationship between offers (i.e., features, support, products) and how a customer journey, from landing to expanding, might work across a portfolio. While solutions or hero products are often the landing point, services or platforms are what expand customer relationships over time. 

For portfolio architecture and naming, we have long guided clients with a foundational rule of thumb: as few brands as possible, but as many as needed. This means that high value, prominent offers are often named in a suggestive or abstract way, creating a distinct brand that can stand out or tell a bigger, complex story. But point solutions, products, or features should often leverage descriptive, unbranded names to simplify navigation and drive clarity for buyers.

The rise of agentic AI does not break this strategy, but it alters how it’s executed. 

For an AI agent to recommend your solution, taxonomy and naming still matter. But how to do both well has shifted. 

As compared to traditional search that emphasizes clear categorical keywords, agentic search has opened the aperture to much more detailed and specific parameters. Shoppers or agents can ask about jobs-to-be-done and desired outcomes, alongside pricing and integration criteria.  

FOR EXAMPLE

Human search: “Best enterprise media planning software for B2B tech”

Traditional Search/Google SEO: “enterprise media planning” or “B2B ad planning” 

Agentic Search Query: “Identify enterprise software or autonomous agents that automate multi-channel media planning, execute real-time cross-platform budget reallocation, integrate with Salesforce Marketing Cloud and Snowflake, and maintain SOC 2 compliance for an annual ad spend exceeding $20M.” 

Of course, names alone cannot communicate everything dictated in an agent search. But descriptive names can be restructured to surface the highest value terms. Names with outcome or jobs-to-be-done terms often work better than broad categorical terms.  

For descriptive names in the agentic era, the delicate dance will be how specific can you be while staying as broadly relevant as possible?  

LLMs rank names with specific action verbs highly; however, this can limit the extensibility of your offer. For instance, a name like “Media Planning & Budget Allocation” would rank higher than “Budget Planner,” but potentially limit a human’s understanding and implementation of the offer against broad applications. Yet overly generic names that suggest a use case, but don’t call it out specifically, like “Pulse,” “Canvas,” and “Compass” will get lost in a sea of similar options for LLMs without more clarity.

This suggests that one of the favored sweet spots for naming, using a suggestive or enhanced descriptive name that’s an easy reference point and vessel to build meaning, may be harder to make work in the agentic era. 

To earn LLM trust, abstract names need external validation, while descriptive names need masterbrand backing.

Suggestive sub-brands offer long-term value by driving ratings around trust, authority, and benefit storytelling. However, AI models in agentic search treat new abstract names as empty vessels unless they are backed by proper marketing investment like  targeted content, customer reviews, and third-party media coverage. Pairing a category descriptor with an abstract name at launch can serve as an effective short-term solution to boost ranking while long-term brand authority builds.

For purely descriptive names (e.g., IT Ticket Automation or HR Scheduler), the backing of a masterbrand becomes critical. Without an explicit connection to an established masterbrand, agentic search systems process these names as functional, generic commodities. Linking descriptive names directly to the masterbrand allows them to immediately borrow its proven trust, perceived benefits, and market authority.

Make your metadata and portfolio linkages work harder.

There are also intentional ways to create clearer connections across your portfolio, so the full benefits that come with any offer are captured by LLMs. Behind-the-scenes levers in your digital presence like correct URL hierarchy that reflects a parent-child relationship between offers, JTBD tagging in metadata, and LLM instructions with offer linkages, can create stronger rankings by LLMs than simply a well-engineered name. 

Operationalizing your strategy for the new dynamic reality.

Governing incoming naming requests can be challenging for marketers at firms with rapid innovation cycles and broad portfolios. Agents can help marketers equip and empower their product counterparts — typically eager to flex their creative skills to name —generate names that are on-brief and in line with their portfolio architecture. By training an LLM on your proprietary portfolio taxonomy, naming rules, and brand voice, you can empower product teams to test and validate names in real-time. This active, co-owned approach ensures that naming suggestions are highly aligned with the core strategy before they ever reach a formal review committee. 

The Unanswered Question for CMOs

FROM TRADITIONAL PORTFOLIO ARCHITECTURETO AGENTIC PORTFOLIO ARCHITECTURE
Primary AudienceBuyer, users, procurement teams (humans) Autonomous AI agents AND human decision-makers 
Naming BiasDistinctive, suggestive brands OR 
Descriptive, categorical names 
Distinctive, ownable brands OR semantically unambiguous names 
Governance ModelCentralized brand teams and guidelines Dynamic, AI-assisted embedded workflows 

As you audit your portfolio for the AI-first market, a critical question remains: Does your current brand architecture help agents understand your value, or is it actively hiding your best solutions behind a wall of semantic confusion? 


FINAL THOUGHTS

At Prophet, we partner with the world’s leading enterprises to design, structure, and govern portfolios built for both human choice and machine discovery.  

To learn how we can help you optimize your portfolio architecture for the agentic era, reach out to us for an agentic brand architecture assessment. 

BLOG

From Chinese Champion to Global Brand: What it Really Takes to Build Relevance Beyond China

International scale is no longer enough: discover the five strategic lessons for Chinese companies to transform product export into enduring global brand equity.

Chinese companies have mastered the mechanics of going global. They can move products, technology, supply chains, and business models across borders at a remarkable speed. This was the first era, built on market access and efficiency.

But international scale is not the same as international relevance. Access is no longer enough. When Chinese companies go global today, they are not only exporting products or business models; they are also exporting a point of view, a promise, and a set of expectations.

The harder task is building meaning, preference, and trust – the things that cannot be shipped as easily as a product. That matters not only for consumers, but also for regulators, investors, and local workforces.

The Next Era of Chinese Globalization Requires Brand-led Transformation.

Through our experience helping Chinese brands strengthen their reputation and salience in global markets, we have identified five lessons that matter when the goal is not just to go global, but to be chosen globally.

1. Start With the Business Ambition, Not the Expression 

Too often, brand work starts with expression before purpose. But a brand cannot be designed in isolation from the audiences it exists to serve.

For Chinese companies going global, this matters even more. The temptation is to define the brand around how it should look or sound in international markets. But the more important question is what the business is trying to achieve over time: where it wants to win, what role it wants to play, and what kind of value it needs to create. That means the brand should not be treated as a final layer of polish. It should be built from the ambition outward.

BYD’s ambition was to electrify transport globally. It first entered overseas markets with electric buses and taxis, building credibility with fleet operators and governments. Passenger cars came later. The brand was positioned around technology, safety, and total cost of ownership. As the business moved upmarket, brand expression evolved – sub-brands Denza and Yangwang convey a carefully crafted premium positioning for overseas markets. BYD’s global brand recognition is an output of its manufacturing and technology excellence, not a simple brand story.

2. Don’t Confuse Awareness with Meaning

Visibility is easy to mistake for brand strength. Sponsorship, media, and distribution can make a company famous quickly. But fame is not the same as meaning or salience, and name recognition is not the same as a reason to choose.

A brand needs more than attention. It needs an idea that people can remember, recognize and trust. That is why a global brand cannot just be a campaign or a visual system. It needs to be an ecosystem of positioning, architecture, identity, and experience principles that work together to create one clear association. The strongest brands do not stop at awareness, they turn visibility into meaning and desire.

Xiaomi’s core association is clear: smart, well-designed technology at accessible prices, connected through a broader ecosystem. That idea has travelled across India, Europe, Latin America and Southeast Asia. Early fan communities helped create advocacy, while a consistent product experience and expanding portfolio of phones, wearables, home devices and scooters all reinforced the same brand promise. Its new EV launches extend that meaning further by bringing high-tech, high-UX mobility to a more accessible price point.

Xiaomi has plenty of awareness, but its brand is not only attention. Consumers choose Xiaomi because they believe they are getting innovation, design and performance without overpaying. That is meaning.

3. Be Globally Coherent, Locally Relevant

One of the hardest tensions in global branding is between consistency and adaptation.

Chinese companies often face this tension more sharply than others because they are expanding quickly across diverse markets, often digitally without decades of inherited brand equity. That means they cannot rely on familiarity to do the work for them.

The answer is to evolve from the generic globalization playbook set by Western brands. It is to define a strong global idea, protect the few things that must remain non-negotiable, and allow the brand to flex where local culture, customer expectations and market context demand it.

That is what it means to be globally coherent and locally relevant at the same time: not uniformity, but disciplined adaptation.

This is where we still need to wait and see which Chinese brands can do it consistently at scale, because most are only just beginning their global brand-building journey. 

4. Turn Aspects of Contemporary China into Brand Advantage

For some Chinese companies – especially in a world of heightened geopolitics – provenance can invite scrutiny. For others, it can create strength. The difference depends on the category, market, and the story the brand is trying to tell.

That is why the question is not whether to be Chinese or global. In some categories, China can signal speed, innovation, technical sophistication and cultural depth. In others, those same associations may need to be translated carefully. Either way, Chinese identity should be assessed strategically, market by market, as part of the brand system.

The strongest brands know when provenance strengthens the story and when it needs reframing.

Songmont is an interesting emerging example of how a Chinese brand can turn contemporary Chinese taste into brand advantage. Rather than leaning on overt national symbolism, it draws on restraint, craftsmanship, materiality, and a quieter form of luxury. That gives it a distinct point of view that feels rooted in Chinese design sensibilities while remaining broadly legible to international consumers. It is still early in its global journey, but it suggests how Chinese provenance can be expressed through taste and philosophy, not only through technology or scale.

5. Global Brand Building Requires Organizational Change

International growth changes who gets to decide what. Corporate headquarters has to loosen control. Local markets have to operate within some boundaries and the company has to find a way to maintain coherence without becoming rigid.

That is why global brand building is never just a marketing issue. It requires changes in governance, ways of working, and equally importantly, culture. It often requires a marketing operating model that can support effective decision-making, ensure efficiency while empowering collaborations across multiple markets.

It also means modulating the employer brand, not just the customer brand. Perceptions of hierarchy, pace, challenge, and empowerment all matter when competing for the best international talent. The answer is not to abandon the culture that drove success at home, but to evolve it consciously.

The Chinese brands that win globally will be those that do not simply attract great international talent, but create a culture in which that talent can thrive – and help shape what the company becomes next.

Midea is a compelling example of what global brand building can look like when market insight, product, and organization come together. The company’s growth is not just a story of exporting appliances; it is a story of building the capability to design for local needs, adapt to market-specific requirements, and compete credibly across markets. The PortaSplit success is a strong illustration: designed in Germany to meet European compliance and user needs, but still anchored in decision-making at China HQ, it shows what a more mature global operating model looks like.

Is your company ready for the new era of globalization? The right strategy starts with six simple but revealing questions about the business, the brand and the organization behind it.

  • What business ambition is the brand being asked to enable?
  • What do people outside China currently know or believe about us?
  • What is genuinely distinctive about us that deserves to travel?
  • How can we translate that into a benefit that matters universally?
  • What must remain globally consistent, and what can flex locally?
  • Do our organization, culture and governance allow us to operate as a global brand?

FINAL THOUGHTS

The strongest Chinese global brands will not be those that become less Chinese, nor those that simply export what worked at home. They will be the companies that know which parts of their identity create value abroad, which parts need to be translated, and what it takes organizationally to deliver that promise consistently across markets. In that sense, the real challenge is not just expansion. It is brand-led transformation – of meaning, of expectations and of the business itself.

The Marketer’s 
Growth Mandate 

With the dawn of AI driving the most significant shift of the century, modern marketing is more capable than ever before. Yet amid the sheer possibility, the discipline has never been more confused about what it stands for. 

This was not always the case. Since the inception of the discipline in 1902, marketing primarily functioned as a growth engine. Nearly a century later in 1999, Sergio Zyman, the CMO of Coca-Cola, who built one of the most effective marketing machines in history, said it plainly: 

“Marketing is about selling more stuff to more people, more often, for more money.” 

More people. More often. For more money. 

Somewhere between Zyman’s era and ours, marketing got distracted by its own complexity. The proliferation of channels and the obsession with immediate-return marketing let go of what it was built for: the mandate to grow the business.

Today, the marketing function is a feat of specialization. Roles are siloed into performance marketing, brand strategy, CRM, social, SEO, content, influencer, data and analytics, and marketing technology. Each discipline has its own metrics, dashboards, agencies, and definitions of success.

AI is accelerating this specialization. Marketers must now feed models and train systems in addition to persuading the humans and organizations that choose and consume. And while AI enables us to produce significantly more ideas and content at speed, it has not yet made us more strategic. We’ve become so focused on “How did this campaign perform?”

This question matters, but it is not enough. The single most important growth anchored question is: 

“How are all of these things, together, changing customer behavior and driving the business forward?” 


The reckoning is getting harder to ignore. Budgets are shrinking, and marketing’s seat at the executive table is becoming less secure.

On the other side of that gap sits a marketing function where only 35% of marketers describe revenue and profit growth as their primary responsibility.

This gap is the central crisis of the modern marketing profession.

Perhaps it’s no surprise that marketing investment has declined from 11% to 7% of revenue, that 55% of marketers cite short-termism as their No. 1 challenge — a figure that has risen thirty percentage points since 2022 — and that resources are being stripped back accordingly. 

This is where we are today, and the only way out is back to where we started — to the original mandate of delivering growth.

This chapter of Prophet’s Modern Marketing Playbook asks us to reconsider some of the marketing fundamentals, refreshed for the modern AI era but grounded in the science of what works to deliver customer-centered growth. 

Each function with a seat at the table owns a distinct contribution to the business. Finance owns capital allocation. Sales owns conversion. Product owns the solution. Marketing’s unique contribution is knowing the customer better than anyone else and using that knowledge to engineer the behavior change that will grow the business.

Zyman’s philosophy is the heart of any marketing strategy: grow the customer base, increase purchases with current customers, or increase spend per occasion. 

The strongest marketing organizations do this deliberately. In our research, 86% of leading marketing organizations report having a shared understanding of the customer across the entire business. Leading marketers also far more likely to be responsible for customer insights — 86% compared with 50% among less effective organizations. This deep empathy and understanding is the spark that unlocks the shift in habit, perception, or need at scale. Uncovering these deep insights remains THE critical moat.

A winning marketing strategy then connects that understanding to measurable business outcomes. The 82% percent of leading organizations tie customer data directly to measurable business outcomes, compared to 59% of others, have made customer behavior the starting point of their growth planning. They then work backwards from a revenue target to understand how many people need to change their behavior to deliver the growth outcomes. This kind of funnel math enables teams to identify the scale of their ambition, to clearly signpost to the organization marketing’s role in growth, and to test whether the resources available are sufficient.

This matters because sustained growth rarely comes from squeezing more value out of a small group of loyal users alone. A widely cited body of evidence from the University of Melbourne’s Ehrenberg-Bass Institute shows that brands grow by reaching and recruiting the broadest possible customer base. With most businesses losing around 30% of their user base each year, this means living in an almost constant posture of recruitment.

But recruitment does not always mean acquisition is the only answer. For some businesses, the largest opportunity may be increasing frequency. For others, it may be expanding spend per occasion or shifting customers toward higher-value offers. The discipline is knowing which behavior matters most and why. 
When marketers define and quantify customer behavior change as the driver of growth, they earn a seat at the table. They are no longer defending campaigns after the fact. They are shaping the growth agenda from the outside in. 

Owning the customer is the first imperative because every other decision depends on it. Once marketers know whose behavior must change, the next question is where that behavior can change. 

Once marketers know whose behavior must change, growth comes from identifying the needs, moments, problems, and occasions where the brand can become more relevant.

“If you don’t know where you are going, then any path will do.” This can be as true for modern marketers as it was for Alice in Wonderland. In a world of infinite choices, deciding which path will deliver the strongest outcomes – and which won’t – becomes even more critical.

Where to Play: Defining the Frame of Reference 

Growth often stalls because marketers narrowly define their “Where to Play,” focusing exclusively on direct competitors within a fixed category. But limiting the frame to the category as it appears only ever surfaces more ways to compete for the share you already hold. Significant growth requires expanding the purposes and occasions you serve, always anchored back to the customer need those occasions are answering. 

Customers don’t think in terms of categories, but in problems to solve, and in the occasions where those problems show up — and how brands can help them solve them. This is achieved by rethinking the Frame of Reference and quantifying the Total Addressable Market (TAM): what market do we play in, and how big is that opportunity? Here, customer centricity becomes marketing’s superpower. 

Consider two in-market examples: 
Baileys Irish Cream: From “Holiday Liqueur” to “Adult Sweet Treat.” 
Historically, Baileys operated in the “special occasion liqueur” category, served over ice after Christmas dinner. By reframing the market opportunity around “adult indulgence” and “liquid dessert,” they were able to source growth from desserts, chocolates, ice cream, coffee moments, and other premium treat occasions. 

Watch the case study here.

Adobe: From “Design Software” to “Marketing Infrastructure.” In the late 2000s, Adobe was primarily known as “creative software” (Photoshop, Illustrator, InDesign) for designers. This was a powerful position, but a revenue ceiling capped by saturation with that group.

As the software market moved toward SaaS, Adobe reframed its full value proposition, bypassing design departments to tap into the much larger CMO customer base. Adobe became a full-stack engine supporting digital customer experience, personalization, and content creation with an all-in-one, connected ecosystem.

Once “Where to Play” is defined, the job becomes mapping how to get there. Owning the growth moves means deciding which actions will change behavior, how much investment they require, and how success will be measured. 


From there, the task is to drive specific actions with the identified growth audiences: 

  • WHAT are the precise jobs to be done with them? What behavior, belief, habit, or decision must shift? For example: increase awareness of a specific attribute. 
  • WHERE will the volume come from? Which competitors, substitutes, behaviors, or non-consumption moments will source the growth?
  • WHY will customers believe in the brand? What is the brand’s advantage, proposition, proof, or experience that makes the behavior change credible? 

Before selecting what to do, marketers must pass through a gate of investment sufficiency. 

F — Future-Back Innovation: Developing tomorrow-ready offers, services, and go-to-market approaches — running at two speeds, executing today’s business model while preparing for market shifts five years out. 
O — Offers & Occasions: Designing a complete architecture of products and services that cover unmet needs and map directly to the specific occasions in which customers purchase. 
R — Route-to-Market & Channels: Optimizing where and how customers interact with the brand. Whether selling B2B industrial minerals or lipstick, the product must be easy to buy, friction-free, and present where customer behavior is shifting. 
W — Whole-Journey Engagement: Mapping and prioritizing activities across the entire customer ecosystem — balancing resources across awareness, consideration, performance, purchase, and ongoing customer experience, rather than over-indexing on one stage. 
A — Amplified Category Voice: Upweighting competitive presence with breakthrough, memorable marketing — modeling spend so overall investment matches ambition (growth usually requires a spend share greater than market share), commanding disproportionate attention. 
R — Reinvigorated Brand Value: Updating the brand to stand for something distinctive, memorable, and relevant, with a clear promise and consistent reasons to believe across all touchpoints. 
D — Digital Demand Generation: Deploying modern, digitally driven engines to actively drive, capture, and convert pipeline — turning general brand awareness into targeted, measurable commercial transactions, while maintaining a balanced brand-performance mix. 

Growth usually comes from pulling several of these levers at once — carefully balancing them to get to optimal outputs. The discipline is building a portfolio that matches the customer behavior change, the occasion opportunity, the competitive context, and the level of investment available. 

That is why brand and demand must work together.

Short-term pressure has pushed many organizations toward demand capture at the expense of demand creation. Performance marketing feels easier to measure, faster to optimize, and simpler to defend. But when performance activity becomes disconnected from brand building, companies risk harvesting demand that already exists while failing to create future demand. 

Our own research in Brand & Demand Love Story found that 90% of winning marketing teams integrate upper and lower funnel. Our work with The Multiplier Effect,” found that marketing effectiveness is highest when brand 
and demand work together, driving 90% higher ROI versus performance alone, increasing the effectiveness of performance marketing by 51%, and building brand pricing power and resilience.

The often-cited benchmark from Benet and Fields, says roughly 60% brand to 40% demand remains directionally useful, with variation across industries.

Measurement must reflect both. Leading organizations are able to hold short-term and long-term KPIs at the same time. In our research, 84% of leading marketing organizations can manage short- and long-term KPIs simultaneously, compared with 57% of average organizations, underscoring the importance of building an evidence-based leading and lagging metric system.

HubSpot offers a useful example of multiple growth moves working together. Originally known as an inbound marketing and CRM pioneer, HubSpot expanded from marketing tool to AI-led customer platform. Its CMO used nearly every growth lever at once: Future-Back Innovation to build Breeze AI, new modular Offers & Occasions for scaling companies, and Whole-Journey Engagement through HubSpot Academy — reinforced by shifting Route-to-Market toward agency partnerships, an Amplified Category Voice through the INBOUND conference, and a sustained Digital Demand Generation engine.

The result was not one isolated campaign. It was a connected growth system that expanded the customer base, increased average revenue per customer, supported multiproduct adoption, and created significant incremental volume via partner networks. 

But even the strongest set of growth moves will be unsuccessful if the organization does not understand, fund, and execute them.


A strategy that cannot be clearly explained will not 
be executed. 


Alignment is a critical part of marketing’s growth challenge. It needs to be intentional and structured, building buy-in and confidence through a few practical, fundamental actions. The first is speaking the language of growth. Marketing leaders need to frame outcomes in terms of revenue, not activity metrics, to build trust with other leaders.

“I have an active seat at the table, and work to shape Marketing’s role in response to our overall enterprise goals and help shape 
our commercial deliverables. Marketing needs to be equally accountable for revenue we are generating.” 
–ALICIA TILLMAN, CMO, Delta Air Lines 


Next is co-creation — building the marketing strategy in collaboration with Finance, Sales, Product, the C-suite, and other functions. Our research has shown that winning marketing teams consistently report stronger cross-functional relationships — not just with the typical sales groups, but much more broadly: Finance (+66%), IT (+71%), Product (+41%). 

“We are focused on bringing the organization on board and showing them what good looks like. In our case, we did the work in a small working group to get alignment and prove the case.”
–DIPTI KACHRU, CMO, Broadridge

And finally is marketing the marketing strategy. This requires simplicity, repetition, and internal storytelling. A complex strategy must be repeated consistently across every stakeholder conversation, every planning cycle, and every board update — making sure the strategy becomes shared language, which leads to execution. 

HubSpot’s phrase “solve for the customer — not just their delight, but also their success” is a good example of strategic language that became organizational language. It was simple enough to remember, broad enough to guide decisions, and specific enough to reinforce a customer-led growth philosophy. 

Dove’s Campaign for Real Beauty offers another lesson. After having rejected the real beauty campaign idea, the marketing team created a film specially targeted at the 12 men on the Unilever board- using their own wives and daughter to demonstrate the intense pressure they felt about the pressure they felt from internal beauty standards. By making the emotional reality of beauty standards visible and undeniable, the team helped the organization understand why the strategy mattered. Once the universal insight was clear, the organization could align behind a creative platform that went on to unlock significant growth and reshape the cultural conversation around beauty. 


The Through Line

Sometimes, when everything is changing, it’s good to go all the way back to the beginning.

When marketing was conceived as a discipline at the start of the 20th century, it was defined as:


That is still the job.


Getting Started: The Questions That Change Everything

  • Can you state your growth mandate in two sentences? What customer behavior are you changing, for whom and toward what business outcome? Have you quantified the scale of change needed? 

  • Do you truly own the customer insight in your organization? How are you making the understanding of who your customer, what drives them and how they behave, an enterprise asset? 

  • Have you framed the market so that you are increasing the size of the pie, not just competing for share?

  • Is your plan pointed at how to change customer behavior? How will you bring more customers, more frequency or more spend per occasion- what are the insights and competitive advantages that will get you there? Do you have sufficient funds to deliver the scale of behavior change needed? 

  • Have you identified a collection of growth moves? Thinking beyond communications to the full F.O.R.W.A.R.D marketing mix?

  • Are you generating future and incremental generating demand, not just capturing existing demand? What is the budget split? If performance is winning by default, customer trust and brand value may be eroding. 
Modern marketing demands a connected system that delivers growth, protects brand, and drives measurable impact at pace. Talk with our experts about how to navigate this AI-accelerated era and build the playbook that works for your organization.

Authors

The Modern Marketer’s Growth Playbook

Fundamentals still matter. But developing new opportunities requires a brand-new game plan, blending best practices with new ones. 

Chapters

Marketing is in the middle of its most consequential reset in decades. Brands that seemed unstoppable a few years ago are melting down. Funnels have collapsed. Algorithms rule discovery. And trust – one of the core tenants of brand marketing – is at an all-time low.

In this rapidly evolving landscape, marketing done right looks different from how it has in the past. It’s not that AI has changed everything. (We don’t buy into that kind of hyperbole, and you shouldn’t either.) Marketing fundamentals still matter, and much of the language is the same. But because fewer of those older assumptions hold, the terrain is full of heightened tensions. Questions like “brand vs. demand” or “human vs. machine” can’t be resolved, because there are seldom either/or answers. These tensions require constant recalibration, as CMOs try to find the most precise fulcrum point for their brands at any given time.

That judgment means marketing leadership is more essential. This is the moment to blend best practices with new ones. Marketing can become even more of a growth accelerator, cutting through to connect with customers in new ways.

To maximize those opportunities-and grow faster-marketers everywhere are being asked to do three hard things, all at once.

Today’s marketer is being asked to deliver three imperatives simultaneously. Each comes with new opportunities, as well as risks.

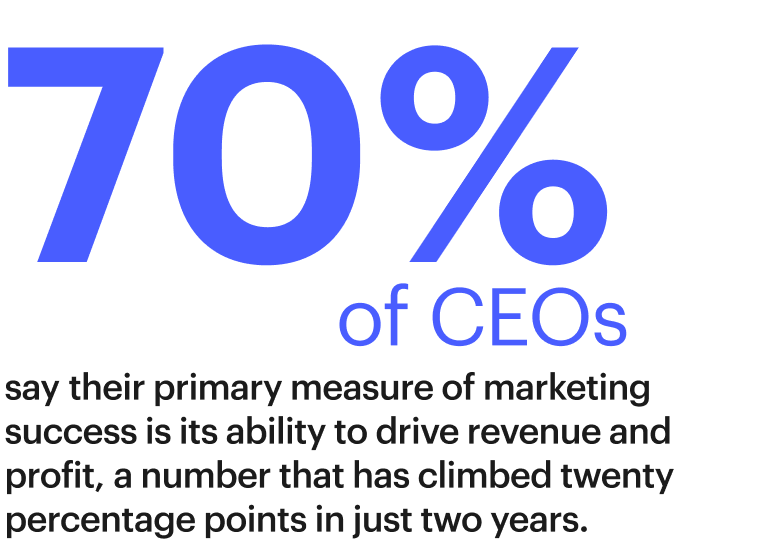
Grow faster, with fewer resources: Growth is the defining expectation of leadership, yet while 76% of CMOs feel more pressure to drive it, only 34% of CEOs agree on how marketing supports that growth. Marketers need to step up, deliver against CEO expectations and re-establish growth as the unequivocal north star. Corporate C-suites are losing faith in marketing, both as a strategic discipline and as an investment: 60% of CEOs view marketing as a cost center, up from 35% last year.

Build brands in an era of compression: Brands are still your most powerful assets, but they are no longer built by stories alone. They are built by signals or what algorithms, and micro-communities decide to amplify. And while 81% of consumers require trust in a brand before purchasing,trust in brands and corporations (as well as experts, governments and the press) is eroding. Culture, technology, and consumer expectations shift simultaneously.

Move from AI Mastery to AI Fluency: AI is no longer a pilot. It is the operating layer of marketing, and 92% of marketers say AI has already impacted their role and 57% feel pressure to learn AI or risk irrelevance. And 72% of CEOs say they are the main decision maker on AI in their organization (2x last year) Marketers navigating this well aren’t the ones with the most tools-they’re the ones who have made deliberate choices about what AI accelerates, what it augments, and what it must never replace.

These forces are interconnected. Growth pressure accelerates AI adoption. AI accelerates content volume and decision speed. That volume and speed intensify brand compression, making coherence and trust harder to sustain.

All three require a faster pace. This is not a moment that rewards perfect plans. It rewards learning velocity, tangible outcomes, and a greater willingness to get it wrong sometimes. That requires marketers to have steelier nerves and stronger stomachs, at a time when the bar is being raised, internally with CEOs and externally with customers. And trust in brands and corporations (as well as experts, governments and the press) is eroding. Culture, technology, and consumer expectations shift simultaneously.

Strategy only matters if it translates into impact quickly. This playbook is designed to help you escape the doom loop by treating brand-building and performance as a single, integrated system.

This new reality needs a new marketing playbook.

SHORT-TERM PERFORMANCE vs. LONG-TERM BRAND BUILDING 

Most marketing teams still divide the world into “brand” and “demand.”  Both our own studies and work we have collaborated on with WARC – including The Multiplier Effect reports – show that outperformers don’t pick sides.  The data shows that brand and demand are not in conflict- but multiply each other, driving 90% increase in ROI than performance marketing alone. Organizationally, winning teams are 3x more likely to be fully integrated (39% vs 12%).

Our research also demonstrated that winning teams use measurement confidence to justify boldness. They work with their CEOs and CFOs to prove the business impact of brand work, ensuring sustained growth. Brand builds the pricing power and trust that make performance work. Performance drives the velocity that justifies brand investment. Treat them as one system, and the short-term pressure doesn’t disappear—it just stops eating your strategy alive.

STRATEGIC SPINE vs.
EXECUTION VELOCITY

Some 73% of marketers say they’re expected to do more with less, and 64% cite proving impact as their #1 challenge.

Speed-to-market is now the mandate, but speed without a spine creates thrash—what we call “random acts of marketing.”

High performers hard code a carefully plotted direction. Just because Speed and efficiency do not render rigor and strategy optional. Making, data and customer insight driven, choices about where to play and how to win, make every marketing activity work harder. This is where AI becomes one of the most important tools that we have helping marketers to ingest and analyze data more quickly enabling stronger decision making and supporting a connected operating system that both thinks and acts at pace- without compromising either

FRAGMENTATION & CHANGE vs.
COHERENCE & CONSISTENCY 

Brands that are consistent over time, with coherent expression across touchpoints, are stronger and more memorable. Yet we now live in a world of “lots of littles.”

At the same time, 66% of consumers expect brands to understand their individual needs.

Volume isn’t the goal—coherent volume is. Scaling junk is expensive. You need a brand system built for these “littles” modular assets, clear rules, and smart data so personalization feels on-brand, not off-script. This is where common language and operating standards unlock the power of AI. 

CONTROLLED ADVERTISING vs. 

CREATOR-LED CULTURE 

Traditional media is losing its grip. Creators and micro-communities now hold the cultural distribution power once reserved for publishers. Short-form video has become the default language.

many brands still try to “manage” creators many brands have yet to get the impact they need.

Culture cannot be bought: Growth requires shifting from “planning media” to “choreographing algorithms.” But that doesn’t mean abandoning branded story telling or driving reach. We have all seen the rise of creators and native social as the dominant way to scale attention in the current world- but data has shown that brand recognition in these formats still lags traditional advertising. Brands need modern- algorithm and AI ready systems that scale—cohesive brand ideas and guardrails and repeatable formats without losing community credibility

BOLD CREATIVITY vs.
THE RISK OF CONFLICT 

As media has become more fragmented and technology more sophisticated, customer attention becomes the currency of success. Impact is only possible if people (and algorithms) notice what brands say and do. Yet, a recent study showed that around half of the advertising was considered neutral, i.e. barely noticeable. It seems, as an industry, we have become better at measuring advertising than making it!

 
Meanwhile, algorithms reward rage, amplifying negative content at least 2x.

This has meant that there is higher risk for brands to get caught in the crosswires of culture wars: the kind of attention that is every marketer’s worst nightmare 

Creativity is not a nice have, but a critical business driver. With > 60% of advertising ROI coming from creative quality, attention winning becomes one of the most important tools in the marketing mix. So, while the feed pushes toward bland or inflammatory, winning brands prioritize being bold without being reckless. This takes a careful balance of research, craft and confidence, while leveraging distinctive brand assets with discipline—and building an operating model that enables creative courage—tight measurement, fast feedback loops, scenario planning and leadership buy-in.

HUMAN MEANING vs.
MACHINE MEDIATION

AI is the new filter between you and the customer, with almost all marketers saying AI has already impacted their role, and that applying AI internally can lift the productivity of marketing spend by anywhere from 5 to 15%.

When everyone has the same tools, insight stops being the edge. The edge is judgment—what you choose to stand for, what you ignore, and where you put firm human checkpoints, so AI doesn’t optimize you into sameness. Brands must win both machine visibility (what AI can find and summarize) and human conviction (what people will trust and buy). 

PERSONALIZATION vs. THE TRUST RECESSION 

The Edelman Trust Barometer shows 63% of global consumers believe media is contaminated with biased information. Add in bots amplifying false narratives and AI-generated content flooding feeds, and you’ve got a trust recession. Every interaction feels like a test.

This is the “head vs. heart” tension. You must use data for precision (the head) but maintain a human promise (the heart) to avoid crossing into “creepy” or “fake.” Trust isn’t earned through what you say in a 30-second spot; it’s earned through living proof-promises kept in product, customer experience, and measurable business behavior.

Modern marketers are already feeling these underlying tensions. Our playbook will walk you through the most essential changes, showing fast and effective ways to blend emerging new practices with what’s already working. We’ll start with growth, the most important mandate, and then cover brand relevance, customer centricity, and achieving 90-day impact. The playbook is open – let’s get to work.

The goal is simple: help marketers lead through the most compressed, algorithmic, AI-accelerated era we’ve seen-by building a connected system that delivers growth, protects and strengthens brand, and produces measurable impact at pace.

Contrary to relentless dystopian forecasts, 
AI is not an existential threat to brands. 

In fact, in a world with fewer symbols of value and intrinsic quality, brands are more important than ever. But they are harder to build and grow. You don’t need us to tell you about this new era of marketing, or to belabor all the ways technology and eroding trust have cratered the landscape. Less clear is what it means for your brand, and more importantly, what to do about it all.

Winning today requires that brands create energy. That means they are consistent, coherent, and compelling – brands that have a sense of being alive in today’s fast-moving culture. Brands need a point of view that sparks curiosity and encourages engagement. That’s how they create communities and draw in kindred spirits. Because they make themselves part of cultural conversations, they are relevant to modern consumers, and they represent businesses well, which makes them growth meteors. Prophet’s ongoing research has found that companies whose brands achieve high levels of relevance a key component of energy – grew 201% faster than the S&P 500 over the most recent five-year period.


Social media has made the need for energy increasingly urgent. This year, the average consumer scrolls through 300 feet of social media posts each day, losing interest in brand messaging in 2 seconds. (For younger consumers, that falls to 1.3 seconds.)

Our playbook for modern marketing outlines seven mandates, all guaranteed to reinvigorate your brand and give it the energy it needs to resonate with today’s audiences.

Start with an unapologetic POV

AI giant Anthropic and Red Bull, a legacy CPG brand, might not seem to have much in common. But both stand out because they understand that brands that appeal to everyone don’t appeal to anyone. They have a beacon specific enough to attract true believers. And both are fast-growing market leaders, despite relentless new competition.

Anthropic has become a trusted AI brand by anchoring in human-centered safety, even amid extreme public distrust of AI and polarizing perspectives on defense. It backs this POV with safety research and concrete policy stances, even when it means defying the Pentagon. That’s resulted in durable credibility, earning preference with builders and enterprises.

Red Bull, on the other hand, stands for adventure, adrenaline and courage – pushing the limits of human ability. Whether it shows up in events (like cliff diving or street dancing), gaming or in retro line-art TV spots, its brash point is unmistakable.

Tech changes make the need for this distinction critical: Algorithmic and cultural fragmentation mean that people no longer share the same spaces. They gravitate towards places where they feel explicitly seen. These consumers can spot a brand poser immediately and will quickly punish inauthentic moves, like pairing with any old influencer rather than someone who offers genuine alignment.

Codify brand behavior

In fragmented, always-on ecosystems, brands aren’t known for one big story. They build their character through repeated patterns of small behaviors, using hundreds of touchpoints.

Brands need to be instantly recognizable: In fragmented feeds, a recognizable brand character creates fast recall and distinctive assets reinforce it. Strong brands maintain that character across contexts, with their personality evident in every micro-moment.

Be strategic in choosing which spaces the brand shows up in and how the brand expresses itself, designing immersive experiences that make the brand felt -not explained-through promotions, events, pop-ups, and other authentic activations.

Even in a low-interest category, we admire how State Farm achieves this. The insurer uses a repeatable character system expressed through the same warm, familiar tone, whether it’s a celebrity in a Super Bowl spot, Jake from State Farm with a cameo in your favorite Netflix show, or talking huskies on TikTok.

SIXT offers another strong example, showing how a brand can stay memorable by being timely, culturally fluent, and unmistakably itself. Its signature orange and premium “Rent THE Car” positioning carry through every touchpoint, from an orange-branded journey between the airport gate and the rental desk to first-class rides during Fashion Week in global style capitals. Across promotions, pop culture-responsive outdoor ads, social commentary, and experiential activations, SIXT consistently behaves like a witty, playful, premium challenger, bringing desirability to a traditionally transactional category.

Think beyond your category

The New York Times may still be a prestigious newspaper in a failing industry. But NYT is a fast-growing brand, beating much bigger tech companies in the fight for daily screen time. Wordle, Connections and The Daily have become rituals for new fans, making the brand indispensable beyond straight news reporting. With popular podcasts and habit-forming audio and video, it’s turned verticals like Wirecutter, The Athletic and Cooking into their own subscription packages.

Using AI-legibility and AEO optimization, NYT is extending its brand by moving well beyond its peers. It understands that its sources of competition have proliferated, and it is successfully competing against anything grabbing people’s attention, including social-media creators, the news, memes, and AI answers. This algorithmic discovery has become the default, constantly raising the bar for attention. In feeds full 
of rage-bait and blandness, only the most distinctive and resonant brands get noticed. Safe creative 
blends in, so standing out now requires bigger, bolder ideas, and the credibility built through coherence 
and consistency.

This requires that brands think like content creators, leading with material that’s inherently appealing to consumers and tailoring it for specific platforms, matching the pacing, tone and conventions of each environment, while bringing value through a unique point of view.

Spotify is another strong example of a brand transcending its category by turning a functional utility into a daily cultural habit. What began as a music-streaming service has become a personalized audio ecosystem built around discovery, identity, and fandom. Playlists, podcasts, audiobooks, and annual rituals like Spotify Wrapped give people new reasons to return, while tools such as AI DJ, AI Playlist, and Daylist make the experience feel increasingly tailored to each listener.

Spotify is also carrying that relationship beyond the app. The Reserved feature uses signals such as streams, saves, shares, and location to give eligible Premium subscribers early ticket access for artists they actively support. Artist profiles create a path to shop merchandise, while Spotify’s logged-in audience powers its growing advertising business through the Spotify Ad Exchange. Moving beyond music streaming, Spotify is a unified ecosystem where people discover culture, express their taste, and deepen fandom.

This requires that brands think like content creators, leading with material that’s inherently appealing to consumers and tailoring it for specific platforms, matching the pacing, tone and conventions of each environment, while bringing value through a unique point of view.

Build in public

When Burger King realized how intensely fans had soured on its once-beloved Whoppers, it could have undertaken a quiet quality-control effort without drawing attention to widespread customer dissatisfaction. Instead, it made a public confession, rolling out a marketing campaign showing how it was rebuilding the sandwich from the ground up, matched by dramatic product changes. The CEO stars in the mea culpa commercials, and even fields phone calls from unhappy diners.

That fans are returning in droves shows just how important transparency has become to today’s audiences. Trust is only earned through consistent, visible actions across multiple channels. Customers want to verify your credibility at any moment. Brand transparency has moved from one-off reports to always-on auditing through reviews, communities, and third parties, both before and after purchase. AI intermediation and distillation only exacerbates this change, leaving no room for significant business missteps that violate consumer expectations.

Trust today requires active renewal, as consumers continuously validate brands by cross-checking 
evidence. Consistency compounds credibility, because many one-off transparency moments don’t survive always-on scrutiny.

That means it’s important to make decisions and tradeoffs visible to your audiences, inviting them to participate in the decision-making process, giving them confirmation that you see and hear them, and letting brand actions deliver the results.

Win decisive moments

The customer journey has collapsed. The journey is no longer linear, and every interaction is its own rapid decision funnel. That means brands now must deliver trust, proof, and purchase affirmation all at once, compressing awareness and consideration, and choice into a single decisive moment. Brands are the medium for building trust equity across all channels, so when that decisive moment arrives, the brand is the clear choice.

GenAI has made this validation a mandate. Consumers triangulate proof with peers, communities, and independent sources before believing a claim. Purchase is embedded in that discovery process: Social content, creator storefronts, and LLM-driven results now include transaction capabilities, enabling people to go from “see it” to “buy it” instantly. Enable low-friction conversion with shoppable content and native checkout experiences.

Grainger, an industrial supply company, embeds deep specs and frictionless purchasing at the exact instant of need, not in some after-the-purchase brochure – meeting consumers where they are, on their terms, with the information and confirmation they need.

IKEA applies the same approach to one of retail’s most drawn-out consumer purchases. Buying furniture has traditionally meant weeks of browsing, measuring, and second-guessing, but IKEA’s app collapses discovery, validation, and conversion into a single flow.

Shoppers can start from inspiration anywhere, even snapping a photo of a piece they’ve seen elsewhere and using visual search to find similar IKEA products. AR and 3D tools like IKEA Kreativ let them place real products in their space to test scale, style, and combinations, and share designs with others for a second opinion. When they’re ready, they can buy directly in the app for delivery or Click & Collect pickup, or scan items as they shop in-store for express checkout. The technology strengthens IKEA’s promise of practicality and accessibility at the exact moment of decision.

Cultivate co-creation

Crumbl has galloped into the newsfeeds of dessert lovers, and it’s not just because of mainstays like Pink Sugar, Milk Chocolate Chip or Cornbread cookies. This brand’s secret is a co-creation strategy made for modern audiences, enabling real-time social and community monitoring that treats audience signals as strategic input. With weekly flavor rotation and limited recipe drops, the cookie company opens up every element for creators and enthusiasts. That includes partnerships with other brands like Dove (Strawberry Crumb Cake Deodorant and Tres Leches Body Scrub, which flew off the shelves). Celebrities and micro influencers also help. And it even harnesses negative narratives, addressing them promptly to accelerate co-creation and transform the dissatisfaction into positive energy.

Crumbl knows its narrative is co-written, not controlled. AI, influencers, and communal sharing mean that messages evolve with every interaction. When done well, co-creators will do the marketing for you. Algorithmic feeds enable audiences to remix, amplify, and reject brand content. Brands succeed by setting clear guardrails for how and when their story travels – and the more authentic, the further and faster that story will go.

Negative sentiment also compounds exponentially, but algorithmic amplification scales bad experiences more than good ones, so brands need strong fundamentals and rapid response capabilities.

LEGO similarly demonstrates how a brand can embrace co-creation at scale. Its LEGO Ideas platform is one example of fan ideas, community participation, and shared creativity shaping both the product experience and the brand story. Any fan can submit an original set concept, and designs that reach 10,000 supporters enter LEGO’s formal review. Those selected become official retail sets, with the fan designer credited on the box and earning a share of the royalties. By treating audience input as a strategic signal rather than background noise, LEGO makes the brand feel co-authored, not controlled.

Negative sentiment also compounds exponentially, but algorithmic amplification scales bad experiences more than good ones, so brands need strong fundamentals and rapid response capabilities.

Keep on flexing

In today’s market, the biggest brand risk is rigidity. Uncertainty is here to stay, which requires building dynamic brand systems that empower teams to adapt fast with confidence, creating asymmetric upside opportunities.

Annual planning cycles matter, but they’re not enough. Brands that win treat data as a creative input, adapting narrative direction based on what is happening right now, and the ways real-time signals are reshaping reshaping brand perceptions. As online forums and feeds generate both positive and negative momentum, brands that engage and channel that energy in real-time have the advantage.

When Vaseline noticed a surge of hacks going viral – more than 6,000 – it saw the trend for what it was: people looking for new uses for Vaseline every day and talking about it in their communities. The company launched Vaseline Verified, a campaign that paired fan-submitted Vaseline hacks with dermatologists, giving the internet clear, credible information.

Heineken shows how a heritage brand can flex its expression without changing its core. Beyond its products, Heineken stands for making social life more rewarding by creating occasions for people to connect, be present, and share experiences. When it picked up on growing smartphone fatigue, it responded with the Boring Phone and a “Boring Mode” app, encouraging people to trade screen time for real-life connection. It carries the same belief into a very different social space, recognizing gaming as a meaningful way people gather and using beer matchmaking and in-game bars to spark connection around shared play.

While its executions span nightlife, culture, technology, and gaming, the brand’s role stays consistent: helping people make the most of time spent together. That balance lets Heineken follow cultural attention while building the long-term familiarity and trust that keep a heritage brand durable.

Getting Started:
Brand energy audit

All seven of these mandates require some new mindsets, new ways of working and capabilities, and teams are still learning what good looks like. But it’s important to note that they draw on a world of truths that aren’t new at all. People are still people. We still seek belonging, community, and intrinsic value. We want signals of quality and shortcuts for trust. Brands must answer those unchanged needs with modern marketing, showing up in ways that are compelling, consistent and coherent, and leveraging their brands as continuing sources of positive energy. The tools are new. The job isn’t.


Here are four questions all marketers should be asking – about themselves, their teams, and their audiences – to make sure their brand has the energy it needs to win. 

Modern marketing demands a connected system that delivers growth, protects brand, and drives measurable impact at pace. Talk with our experts about how to navigate this AI-accelerated era and build the playbook that works for your organization.

Authors

BLOG

To Avoid AI Lock-In, Companies Must Own The Workflows That Create Their Value

Why enterprise AI-agent strategy depends on flexibility, measurable impact, and owning proprietary workflows.

This article was originally published by The Intelligence Record.

“You cannot outsource how you do business. LLMs are generalized machines. If you do the hard work of figuring out your workflow and translating that into an agentic workflow, you’d want to own it.”

Chan Suh, Chief Digital Officer, Prophet

As companies move past their initial AI experiments, executive teams are taking a harder look at token limits, monthly bills, and the very real threat of vendor lock-in. While deploying agentic workflows is becoming a standard approach for corporate agility, it doesn’t mean a company should outsource its core operations. For organizations with highly specialized workflows, defaulting to off-the-shelf generalized models usually means handing over control of proprietary business logic. Scaling AI tools effectively hinges on the decision of exactly what to own versus what to rent.

Chan Suh has seen these cycles before. Back in 1995, he co-founded Agency.com with $80 and rode the early dot-com boom all the way to a NASDAQ IPO, growing the business to 1,800 employees and $200 million in profitable revenue. Today, as Chief Digital Officer at Prophet, he helps enterprises navigate the current tech wave. Drawing on decades of scaling business value, Suh advocates for definitive ownership over proprietary AI.

“Just because you can adopt AI doesn’t mean you should. It’s going to be very important for enterprises to understand how to use agents and what parts of their work, whether it’s in supply chain or marketing or anything else, can be helped by agentic workflows,” he says. Suh views the discipline of deciding where agents genuinely help before deploying them as the foundation for every other decision that follows.

Ownership of the Workflow is Ownership of the Business

Suh’s central argument is that a company can’t outsource its most intelligent piece. How it does business, creates opportunities, fulfills customer expectations, and runs the processes that make everything work isn’t something a generalized model should own. “You cannot outsource how you do business,” he asserts. “LLMs are generalized machines. If you do the hard work of figuring out your workflow and translating that into an agentic one, you’d want to own it. That ownership is super important.”

What has changed is the cost of that ownership. Building proprietary workflows into machine systems used to require translating the process, building the interface, testing it, and evolving it, all of which made ownership prohibitively expensive. Thanks to AI, that work is now within reach for companies of nearly any size. “If you make it, you get to keep it. The thing that makes your company do what it does super well, you get to keep it. And the cost of making it is not nearly as expensive as it used to be.”

The Dependency Risk Hiding in Subsidized Pricing

The strongest case for preserving optionality is economic. Suh warns that current token pricing for frontier models is subsidized, and companies building their futures on those prices are exposed to a cost structure outside of their control. “At some point somebody has to pay for it. If you’ve been modeling your company’s future on these LLMs, what happens when they come back and say, ‘Sorry, it’s 4x what you used to pay’? Is that the future you want to build for yourself? Do you at least want an escape hatch?”

The escape hatch is a proprietary or captive model. With open-source LLMs now available to be trained, Suh envisions a future where companies of any size run their own captive model for proprietary and non-frontier work, reserving the expensive frontier models only for the tasks that genuinely require them.

The provider-incentive problem is why he’s skeptical of letting the large model companies design an organization’s agentic infrastructure. “Asking large LLMs to create your agentic infrastructure is like asking oil companies to design your cars. It’s going to be super fast and super exciting and loud, but it’s also going to be a huge gas guzzler, because that’s how they get paid.” The performative version of AI adoption, announcing a marquee deal to satisfy the board for two quarters, eventually comes due when someone asks whether the company actually made progress.

Impact Before Tools

The measurement discipline Suh advocates inverts how most companies approach AI. The question is not how to become more AI-powered, but what AI can do for the specific business. “Then you figure out what flavor of AI you need. If you’re a straightforward manufacturing and distribution company, do you need something that can solve quantum physics? Maybe that’s overpowered,” he says.

He frames the principle as impact before tools: define the impact you want, then find the tools to create it, rather than adopting capability for its own sake. Adoption metrics are not enough because adoption doesn’t measure progress.

In Suh’s view, the most accessible starting point is high-volume data analysis that humans can’t realistically perform. A company with 100 salespeople can’t digest every weekly sales report, but an agent pointed at that information stream can find the patterns and surface what leadership needs. That work requires little infrastructure investment and delivers immediate value.

Embedding proprietary knowledge is the deeper layer, and it has also gotten dramatically cheaper. Suh estimates the technology to run the basics of a custom AI deployment now costs below a million dollars a year, putting it within reach of companies that need to decide where their proprietary knowledge lives and what they want to keep.

Stop Planning, Start Executing

Suh’s guidance for companies beginning this transformation is to compress the time horizon and act. Because no one can predict the AI landscape five or ten years out, the right question is what a company can do in the next 24 months to maximize optionality while accelerating efficiency. “Companies need to understand what they can do right now, how they’ll measure it, and build on those successes,” he advises. “Stop doing pilots. Pilots are a great way to avoid accountability. Do the things you know you can do.”

Suh’s warning against ten-year infrastructure plans is pointed. The old model of cementing a technology architecture for a decade is, in his view, a fool’s errand in a landscape moving this fast. The better path is measurable progress in six-month increments, delivered through partners who preserve independence rather than trapping the client inside a single ecosystem. “Find the partners who can help you do it at a reasonable cost while preserving technology independence, so you don’t get captured. Do some things right. Stop drawing plans.”

The proliferation of frameworks, Suh notes, is itself part of the problem. Anyone can now generate a strategy document in minutes, but that doesn’t make it good. The advantage goes to the companies that execute against measurable impact while keeping their options, and their proprietary workflows, firmly in their own hands.


FINAL THOUGHTS

Let your people (and your agents) do the work they were meant to. Prophet gives you both the marketing and AI expertise that can help you create business impact. Learn more about our AI Solutions and how they can help drive uncommon growth for your organization.

BLOG

The Importance of Naming in Today’s M&A Megadeal Environment

Five Best Practices That Inspire Brand Confidence 

The global mergers and acquisitions (M&A) sector is rebounding toward a projected $4 trillion in total deal value for 2026—its strongest showing since 2021—megadeals over $5 billion now account for nearly half of all transaction value. And not surprisingly, artificial intelligence is actively reshaping this landscape, particularly in power infrastructure and AI data centers, as traditional software cools. While not every deal requires naming, large transformation deals do. For these record-breaking transactions, securing a new name remains the most visible, symbolic, and long-lasting decision of the merger. But shockingly, many companies still get it wrong. 

Getting to a great name in these fast-paced and high-stakes environments requires significant care and attention. What sometimes starts out as “let’s brainstorm and come up with something cool” can often turn into a highly emotional, intensely subjective process that can create leadership friction and decision-making paralysis, ultimately delaying a brand’s launch.  

The following are five best practices to get M&A naming right:  

1. M&A naming is not a democracy. 

Since naming a new enterprise is something most executives experience just once in their careers, many leaders don’t want to make the decision alone, and invite stakeholders from every function to weigh in. However, there will likely already be numerous decision-making voices at the table—including multiple CEOs, private equity partners, other investors, or board members. In these multi-stakeholder environments, we believe the decision-making body should be kept to the right balance of as few executives as possible, but as many as necessary, with focused participation early in the process (yes, even CEOs).  

Despite the perception that naming is a fun and creative exercise, the reality is, it’s a high-stakes, subjective decision that will carry your organization into the next several years, possibly decades. A smaller decision-making team that is engaged from the outset is more likely to reach a successful outcome.  

Resist the temptation to test name candidates with employees. While inclusion is a noble goal, employees are ultimately the audience for a reveal, not decision makers in the process.  

2. The name you want is probably taken, but there’s a better name out there that isn’t. 

This one is a tough pill to swallow. But with most M&A deals being highly global, getting a name to clear across many trademark classes and geographies requires deep, divergent thinking. Many intuitive, metaphorical names, like, ‘Mosaic’, “Fountain” or “Iris” are taken and trademark exceptions do not exist. 

But by exhausting creative exploration, you can uncover an adjacent or new idea that tells an even richer story. Sometimes a simple, metaphorical real word is still available;  

other times, a coined, ‘sticky’ term or more abstract name offers stronger ownership potential. 

With an estimated 360 million companies in the world, naming isn’t just a creative game. It’s also a numbers game. And arriving at an answer that is inspired, strategic and viable requires diligence, objectivity and a willingness to push past your comfort zone. 

Nearly every name carries some degree of risk. No name receives a complete “all clear,” so involving legal teams early helps define acceptable risk levels and shape exploration. What’s more, different legal teams may employ different legal strategies to pursue or secure a name, from acquiring a mark to petitioning for co-usage with another party.  

When Google launched Alphabet, it couldn’t secure  alphabet.com or the pure social handles, which were currently being used by other organizations with the same name, including a division of BMW. They proceeded anyway, because launching with the very clever www.abc.xyz, because it believed the name best expressed its story. All to say, legal baggage associated with your favorite names can be investigated and often worked around, as long as you have legal embedded in your process from the very beginning. 

4. Fast-paced M&A deadlines can work in favor of a successful naming outcome.  

The deadlines surrounding deal closings and brand launches can make naming feel daunting. We believe sticking to an objective process and clear naming brief enable teams to use time pressure constructively. Having less time often leads to more objective decisions, less room for emotion and bias, and faster alignment. When there is no time to second-guess or decide by consensus, teams often trust their guts and arrive at impactful answers. 

5. And finally, remember that a name is a powerful asset—but not the only asset. 

Although we always say your name is your most visible asset, it is not your only asset. This is especially important in M&A, where multiple parties unite around a broader, more aspirational value proposition. While the name can certainly signal part of this new experience, it cannot tell the complete story on its own. We help clients see their name in the context of other strategic levers, like the promise they make to their customers, their visual language, or the experiences they aim to create.  


FINAL THOUGHTS

Naming in M&A is challenging, but launching a new global brand with a name you feel confident in remains one of the most rewarding parts of the process. To find out more, visit our M&A Growth Acceleration hub. 

BLOG

Beyond the Logo Change: Maximizing Brand Value in Banking M&A

Three moves to strengthen the integration journey. 

Bank consolidation continues, driven by cost pressures, regulatory requirements, and modernization demands. Mergers and acquisitions are on the rise, yet while leadership focuses on financial and operational integration, customers judge M&A success by service continuity. In moments of transition, brand acts as the primary signal of stability, indicating whether an institution remains reliable, transparent, and in control while backend systems shift.

Most mergers treat brand as a cosmetic exercise, updating logos, signage, and website headers, rather than as a living operating system. However, brand trust is tested in daily touchpoints (i.e., ATM withdrawals, mobile app logins, customer support calls) and major milestones (i.e., mortgage applications, account setups). The problem is that when brand strategy is sidelined during integration planning, minor technical issues can quickly become major trust deficits.

To protect customer retention and maintain confidence, brand must be treated as a core operational pillar from day one. Here are three moves that strengthen the brand and maximize value throughout the integration journey:

Move One: Balance Short- and Long-term Messaging

As soon as an announcement lands, customers, employees, and investors begin forming expectations. Their immediate questions are practical: what will happen to my accounts, benefits, and access to services? Will this bank still feel dependable in the months ahead? While some uncertainty is inevitable during integration, the transition represents a unique moment to define a compelling new story of value.

Running two narratives in parallel, reassuring stakeholders about what remains stable while clearly articulating the greater value, helps maintain confidence today and build belief in the future.

Short-term communications reduce anxiety, while long-term vision builds buy-in. If you only focus on operational stability, customers see no upside to the merger. If you only market future benefits while digital tools break, customers feel misled. Balancing both is critical. UBS’s integration of Credit Suisse offers a strong example of how to manage this transition effectively.

What good looks like:

  • Create a two-horizon narrative. One stream should provide reassurance and continuity, explaining what stays the same, what’s covered, and where customers can get support. The second should articulate the longer-term value of the merged organization: what will improve, why it matters, and what it means for customers.
  • Map promise versus experience across key moments: Pay particular attention to moments in the customer journey that already generate anxiety, like onboarding, account transfers, first service interactions, branch and call center support, and communications about fees or rates. Assess how these experiences will change and proactively address any gaps or unavoidable disruptions.
  • Align internal decisions with customer messaging: Customers should clearly understand what is happening today and how these changes affect them.

Move Two: Understand the True Value of Branded Assets

In M&A, branded assets can look like operational details: logos, systems, and channel experiences. In reality, they carry far greater value. They represent years of accumulated reliability and performance, often reinforced through customer habits and expectations. When that value is mishandled, customers don’t just perceive a visual change; they begin to question the institution’s competence and dependability. Integration planning should therefore treat brand as a visible signal of how the organization is managing the transition and what it means for customers and employees, not merely as a design decision.

What good looks like:

  • Understand what each brand stands for: By understanding how brands and assets within the portfolio drive preference, revenue, and pricing power, organizations can better define their future roles and manage expectations throughout the transition.
  • Audit brand beyond marketing: Look beyond physical branded assets to understand how scripts, escalation procedures, service recovery processes, branch and call handling behaviors, tone of communications, and digital experience cues influence customer perception.
  • Decide the end state and guardrails early: Clarify the brand strategy and architecture early. Then design a transition plan that minimizes confusion by considering  how customers experience brands across channels, systems, and journeys.

Move Three: Power Brand From the Inside Out

In the integration’s “messy middle” customers experience the transition through people. They notice when employees can explain what’s happening, handle exceptions with confidence, and recover from service failures. Yet employees are under pressure themselves, navigating ambiguity while learning new tools, adapting to new processes, collaborating with new colleagues, and responding to customer concerns, often before all decisions have been finalized.

Internal enablement must precede external marketing; otherwise, rebranding risks becoming an empty shell. Organizations that take a holistic approach to culture building and harmonization are far better positioned to deliver their brand promises. Prophet’s Human-Centric Transformation Model outlines how to do this effectively.

What good looks like:

  • Translate leadership intent into day-to-day behaviors: Clarify what change means for employees, what decisions they are empowered to make, and what standards they are expected to uphold.
  • Build day one enablement: Develop scripts, decision frameworks, governance structures, and service recovery playbooks, so frontline teams aren’t left guessing under pressure.
  • Synchronize internal and customer-facing communications: Employees should always understand what is happening and how to explain it clearly to customers.

FINAL THOUGHTS

The real test of a merger begins after the deal closes. Brand has the power to turn a period of uncertainty into a moment of confidence and growth. For more perspectives on accelerating value creation before, during, and after a transaction, visit Mergers & Acquisitions: A Path to Uncommon Growth.

BLOG

Lessons From Switzerland’s Most Influential Marketing Leaders

What 16 conversations revealed about AI, brand, and the job that’s quietly being reinvented.

Switzerland is home to a remarkable concentration of globally influential companies, many of which are at the forefront of change. The forces reshaping business today, from AI and shifting customer expectations to growing pressure for measurable growth, are also redefining what marketing leadership looks like. While much of the international marketing world is still debating what comes next, many Swiss organizations are already building it.

This year, Prophet sat down with marketing leaders from multiple global organizations headquartered, or with a significant presence in Switzerland. These included prominent, household names across banking, insurance, retail, telecoms and media. We were not looking to validate a hypothesis, but to listen.

What emerged revealed not only how the mandate of modern marketing leadership is evolving but also offered valuable lessons for leaders far beyond Switzerland’s borders.

The Job Description Has Changed. Most job Titles Haven’t Caught Up

The leaders we spoke to are running functions that look nothing like the marketing departments of ten years ago. One has absorbed IT. Another owns product. A third sits on the executive board and reports directly to the CEO. The scope has expanded well beyond campaigns and brand guidelines, covering growth, marketing transformation, customer, technology, AI, organization, and the wider commercialization of marketing.

One leader described it plainly: marketing without technology fluency is a support function. Technology with marketing judgment is a growth function. The firms that have figured out the difference are pulling ahead.

This is a universal trend that these global organizations are stress-testing in real time.

AI Is Further Along Than Most People Admit, Including The People Running It

When we started these conversations, we expected to hear about pilots, roadmaps, and cautious optimism. What we found were organizations already running AI across content production, customer service, localization, CRM, and product photography. Not experimenting, operating.

One bank built a proprietary content tool that has driven a 40% improvement in production efficiency. A luxury goods brand replaced significant portions of its e-commerce photo shoots with AI-generated imagery. An insurer is using AI to process market signals and generate real-time communications — a system designed to function regardless of what the macro environment throws at it next.

What’s notable is that none of these were pure marketing initiatives. The strongest examples came from teams that had pulled together marketing, IT, and data under a shared model, not from marketing departments that had gone off and bought tools on their own.

The harder problem, consistently, was not technology; it was skills, governance, data quality, and getting an organization to actually change how it works. Technology is the easy part. That sentiment surprised many of the leaders we interviewed when they said it out loud.

CFOs Are Asking Harder Questions. The Best CMOs Already Have The Answers

Every conversation touched on measurement, usually within the first ten minutes of our interviews. Marketing budgets are being scrutinized more carefully than at any point in the last decade, and the pressure is coming from finance, not just C-suites.

What separated the organizations that are winning this argument from those still having it: the ability to connect brand investment to numbers that finance cares about. CFOs are not interested in brand health scores presented in isolation; they are asking marketing to present regression models that tie brand perception directly to net new money, customer acquisition, and retention.

One organization built a Brand Likeability Index consisting of 12 dimensions derived by analyzing which brand attributes actually predict sales. Furthermore, it uses the index to demonstrate that marketing contributes roughly 20% of commercial outcomes. This type of metric generates a very different, and more productive investment conversation than a slide about awareness.

The debate has moved, and it is no longer whether brand investment matters. It is whether the person making the case can prove it in language that travels across the boardroom table.

Trust is not a value. It’s a strategic position. And it’s under pressure

AI came up in every single conversation. But more interestingly, what came up just beneath it, in almost every conversation, was trust.

Swiss organizations have a particular version of this problem. Precision, reliability, and long-term thinking. These are not brand values they invented, they are brand perceptions that took decades to build, and that clients across Asia, the Middle East, and Europe actively seek out. In a period when geopolitical uncertainty is driving capital toward stability, being Swiss is doing real commercial work.

But the same organizations are now deploying AI at scale to produce content faster and in greater volume. And several leaders are  asking the question that doesn’t yet have a clean answer: at what point does automation start eroding the very quality signals that justify the premium?

The most thoughtful leaders are not treating these as opposing forces. They’re treating AI as the production engine and human judgment as the editorial layer — the thing that decides what goes out, not just whether it was generated efficiently. Strategy and creativity at the front while Automation is at the back. The hard work is getting that division right and holding it.

Where Action Is Outpacing Conversation

The leaders we spoke to are not doing press releases about their AI transformations or launching highly visible innovation programs. That restraint is partly cultural, but it also reflects something real: the work is happening, and it is happening quietly. While other markets debate whether AI belongs in marketing, several Swiss organizations are already figuring out what comes next. That, more than any specific tactic or framework, may be the thing worth paying attention to.

Download
Uncommon Growth in Uncommon Times in Switzerland

*Fill in all required fields

Thank you for your interest in Prophet’s research!

FINAL THOUGHTS

The next generation of Swiss marketing leaders is already operating differently: more comfortable with ambiguity, and more focused on connecting the right capabilities than controlling every variable. Download the full findings to explore what these shifts could mean for your own growth agenda. 

Your network connection is offline.

caret-downcloseexternal-iconfacebook-logohamburgerinstagramlinkedinpauseplaythreads-icontwitterwechat-qrcodesina-weibowechatxing