In a world that feels constantly in crisis mode, premium and luxury consumers are looking for far more than a destination. What matters most today is stability, mental relief and, paradoxically, a renewed desire for simplicity and freedom from complexity, a notion that long seemed outdated in the luxury segment.
Prophet’s 2026 Consumer Generation Study makes one thing clear: the luxury market remains a “rock in the surf”, in other words, a resilient segment in an otherwise volatile environment. While the broader market is stagnating, 39% of premium and luxury consumers plan to increase their spending in 2026. Yet brands hoping to capture this affluent audience must recognize a fundamental shift: the definition of luxury has changed.
A New Definition of Premium Travel
In our recent study, Why Reassurance Matters More Than Status in Today’s Premium and Luxury Market, we explore how brand dependability has become a luxury in its own right during uncertain times. The latest data reinforces that trend and reveals just how profoundly perceptions of premium and luxury continue to evolve.
Today, reassurance extends beyond physical safety. It encompasses emotional well-being, reliable climate conditions, and the right balance of human interaction, offering consumers an alternative to feeling overwhelmed by anonymous technology or AI. This change is reflected in six key findings:
1. Premium and luxury consumers defy market volatility
Despite economic uncertainty, spending intentions remain remarkably resilient. Premium and luxury consumers continue to demonstrate strong willingness to spend, making this one of the most stable customer segments in 2026.
2. Mental wellness is now a core travel motivation
Travel is increasingly viewed as a pathway to emotional balance and recovery. While 56% of consumers seek physical rejuvenation, nearly as many (55%) are looking for inner balance, personal meaning, and mental restoration.
3. “Coolcations” go mainstream
Climate change is reshaping travel behavior in tangible ways. In 2026, 39% of luxury travelers deliberately choose cooler destinations or travel periods to avoid extreme heat. Among Millennials, that figure rises to 44%.
4. Luxury cruises continue to gain momentum
With 36% untapped demand potential, luxury cruises remain a significant growth opportunity, particularly among travelers over 40.
5. The package holiday is making a comeback
Especially among younger consumers, simplicity and predictability are becoming increasingly valuable. As a result, the traditional package holiday is experiencing a revival.
6. Tech & touch becomes the new standard
Affluent travelers readily embrace AI-enabled tools and digital services, yet personal interaction remains a critical source of trust and reassurance. The future belongs to brands that successfully combine technological convenience with meaningful human connection.
At the same time, sustainability remains important, but it is no longer the primary decision-making factor it once was. Since 2020, the share of premium and luxury consumers willing to pay a premium for sustainable travel options has fallen from 51% to 39%. Even more striking is the decline in consumers willing to modify their own travel behavior for sustainability reasons—from 45% to 30%.
From Insight to Action: What This Means for Travel Brands
These findings point to some clear opportunities for travel and hospitality brands. To stay relevant and competitive in 2026, companies should focus on six key priorities:
1. Understand the unique dynamics of premium and luxury consumers
In a challenging economic environment, premium and luxury consumers remain among the most resilient customer groups, with a sustained willingness to spend. Successfully engaging this audience requires a sophisticated understanding of how premium and luxury truly work—from brand storytelling and the luxury codes that signal quality, exclusivity and desirability to the many distinct expressions of luxury across generations and consumer segments.
2. Meet the growing need for mental wellness
Wellness is no longer a spa offering—it is a core demand driver. Companies must develop experiences that help travelers recharge emotionally and mentally, whether through retreats, mindfulness programs or digital detox experiences.
3. Innovate around the “Coolcation” trend
While sustainability may be losing some of its pulling power, climate concerns are influencing traveler choices in new ways. Brands should create and actively market compelling experiences in cooler regions and destinations.
4. Bring the package holiday back—differently
When everyday life feels increasingly demanding, travel should feel effortless. The package holiday needs to be reinvented as a premium convenience product—one that satisfies the growing desire for stress-free experiences and reduced complexity.
5. The luxury cruise market has untapped potential
For operators, this is a call to action to find ever newer and smarter ways to unlock that potential. And for those who are not yet active in this market, it may be a signal to reconsider that decision, possibly with an innovative offering aimed at the under-45 target audience.
6. Build hybrid models: tech & touch
The industry must find a new balance between convenience and trust. AI-powered tools drive efficiency, particularly among younger audiences where adoption rates reach 34% among Gen Z. At the same time, personal service remains highly valued by older travelers. Around half of Baby Boomers place greater importance on human interaction than Gen Z consumers do. Across generations, human connection continues to provide trust, guidance and reassurance.
Final Thoughts
The luxury travel market of 2026 is not defined by extravagance. It is defined by resilience. The brands that win will not be those that offer more complexity or more status signaling. They will be the ones that reduce friction, provide genuine emotional reassurance and help consumers navigate an increasingly uncertain world with confidence.
Four Conversations About the Future of Growth at Cannes Lions
What everyone was talking about at Cannes Lions this year.
Walking into Cannes Lions this year, I expected every conversation to revolve around AI. In one sense, it did.
Whether I was listening to Tiffany Rolfe and Nick Pringle at R/GA, Carla Hassan at JPMorgan Chase, Patrick O’Keefe at e.l.f. Beauty, Mark Kirkham at PepsiCo, leaders from McLaren Racing, Mars, SharkNinja, or the CMO Accelerator, AI found its way into nearly every session. But by the end of the week, I realized the technology itself wasn’t the most interesting part of the conversation.
What stood out was how consistently leaders from completely different industries were asking the same question: How do brands create growth in a world where AI is changing not only how organizations work, but how consumers discover, evaluate and engage with brands?
That shift felt remarkably consistent with what we’re seeing in our own work at Prophet and our clients. As AI becomes embedded in both enterprise operations and everyday consumer behavior, competitive advantage isn’t just about adopting new technology. It’s about rethinking how brands earn relevance, build trust and create value in an AI-powered world.
Across four days, four themes kept surfacing.
1. Judgment is becoming a competitive advantage.
One of the biggest surprises wasn’t how enthusiastic marketers were about AI. It was how disciplined they were about its limitations. At R/GA, Tiffany Rolfe and Nick Pringle challenged the industry’s fixation on outputs. As AI makes execution faster and more accessible, they argued that judgment, taste and strategic thinking become even more valuable. One line that stayed with me was their challenge to move from “making things” to “making things that make things.”
That same tension surfaced during the CMO Accelerator, where one participant observed that AI allows good marketers to produce mediocre work much faster. The challenge isn’t creating more. It’s maintaining the standards, curiosity and conviction to create work that is genuinely distinctive.
The conversation has clearly evolved. The question is no longer whether AI can generate content. It’s how organizations use AI to make better decisions, uncover better opportunities and create better work.
2. Relevance is replacing reach.
If there was one word I heard repeatedly throughout the week, it was relevance. Mars captured it perfectly: “You cannot buy relevance. You have to earn relevance.” The same idea surfaced in very different ways across the festival. Mark Kirkham, CMO of PepsiCo Beverages, argued that brands don’t create culture; they earn the right to participate in it. McLaren Racing shared how it has expanded Formula 1 beyond race day, creating opportunities for fans to engage through entertainment, fashion and partnerships. Even CeraVe’s activation around the NBA Finals succeeded because it felt native to a cultural moment people already cared about rather than interrupting it.
That feels especially relevant as consumers increasingly discover brands through AI-powered search, creator recommendations and algorithmic discovery. Visibility alone won’t create growth. Brands need to be relevant enough to be surfaced, trusted and ultimately chosen.
3. Creators are becoming strategic growth partners.
One of the biggest stories at Cannes wasn’t simply that creators were literally everywhere. It was that their role had fundamentally changed. Conversations with creators Josh Richards and Johnny Harris, Kevin Durant and Rich Kleiman of Boardroom, alongside announcements from platforms including YouTube, TikTok and Amazon, reflected a broader shift. Creators are no longer being viewed simply as media channels or campaign extensions. They’re increasingly becoming long-term partners in building communities, trust and brand ecosystems.
That has meaningful implications for CMOs. As the customer journey becomes more distributed, brands are no longer the sole authors of their story. Growth increasingly depends on designing systems where creators, employees, customers and communities actively participate in building the brand alongside the organization itself.
4. AI is accelerating the need for stronger foundations.
Perhaps the most unexpected conversations all week weren’t about technology at all. They were about organizational design. At Jim Stengel’s final CMO Accelerator, discussions focused less on AI tools than on talent, workflows, governance and operating models. One speaker made a point that echoed throughout the week: transformation doesn’t begin with technology. It begins with people, ways of working and how decisions get made.
That observation helped connect many of the conversations I’d heard throughout Cannes. AI isn’t replacing the fundamentals of growth. If anything, it’s reinforcing them. As more content is created by AI, agencies, creators and internal teams, the need for a clear brand strategy becomes even more important. As consumer journeys become more fragmented, understanding what your brand stands for becomes the anchor that keeps every touchpoint aligned. In many ways, AI isn’t creating entirely new challenges. It’s exposing the importance of solving long-standing ones.
Walking away from Cannes, I expected my biggest takeaway to be about AI. Instead, I left thinking about this new era of growth and creativity.
The conversations that stayed with me weren’t really about prompts, copilots or models. They were about judgment, relevance, creators, trust, and organizational transformation. Different industries, different speakers and different examples all pointed toward the same conclusion: AI is raising the bar for what great marketing and creativity looks like.
For Prophet, that reinforces something we’ve been exploring through our work with clients around uncommon growth. The opportunity isn’t simply to use AI to do today’s work more efficiently. It’s to rethink how brands create value for a consumer whose expectations, behaviors and decision-making are changing just as quickly as the technology itself.
That, more than any product announcement or keynote, felt like the defining conversation at Cannes Lions 2026.
How to grow in an ever-changing world? The Uncommon Growth Playbook for a New Era
There’s never been more risk to, or opportunity for growth than there is today. Today’s business leaders face a profound intersection of disruptive cultural, technological, political, and economic forces that can upend longstanding business models overnight. The traditional approach to growth and innovation that worked over the past 20 years has been upended as disruption is not just coming from new products, but new business models and cultural movements traveling at warp speed, entirely changing the rules of the game.
Our research confirms that this is not only possible amid this disruption but is already being proven. In our “Uncommon Growth in Uncommon Times” study, Prophet identified 179 S&P 500 companies that have delivered what we call Uncommon Growth. We characterize this as exceptional growth (averaging 2x their industry peers) that is sustainable (maintained over five or more years), and durable (persisting through disruption). These companies span industries, sizes, and stages. They aren’t outliers by luck. They’ve made deliberate choices that set them apart and build their growth strategy on a compelling story of value.
Through work with organizations around the world, we’ve defined five plays that enable leaders to attain Uncommon Growth. These five plays represent critical shifts in how leaders gather intelligence, frame their market, design their businesses, target customers, and build internal momentum. Together, they distinguish today’s uncommon growth leaders:
Shifting from a product and service only focus to orchestrated platforms and AI native offerings that create and capture value across every point of engagement
This is not a linear formula. It’s a new and essential toolkit that leaders can tailor to their business model, organizational maturity, and industry, and each is designed to drive speed to understanding and impact, using both analysis and embedded AI.
Throughout this playbook, you’ll find examples, measurable impact and actions to move from ambition to outcome. Uncommon growth is not a theory. It’s the disciplined execution of the right moves, at the right moment, for your unique organization.
Always-On Human Insights From Discrete Research to Agentic Intelligence
Today’s customers aren’t just changing faster—they’re living through a world that changes around them every day. New technologies, shifting expectations, cultural moments, and economic pressures continually reshape how people think, choose, and buy. For growth leaders, the challenge isn’t a lack of data. It’s developing a deep enough understanding of people to keep pace.
The opportunity for growth leaders is unprecedented—but realizing it requires rethinking how organizations build empathy with customers and translate that understanding into action.
The companies that win won’t simply collect more data. They’ll have greater organizational empathy—the ability for every product manager, marketer, strategist, and executive to more deeply understand the people they serve and create experiences that feel genuinely relevant.
To drive uncommon growth, leaders must build empathy with their customers and treat customer intelligence as a live utility — not a periodic input. This requires a fundamental shift from discrete research to market sensing and customer intelligence, executed through three core actions:
1. Go deeper to understand people more completely.
Organizations have access to richer sources of customer understanding than ever before—from first-party data to qualitative research and the broader economic, cultural, and social forces shaping people’s decisions. AI makes it possible to connect these signals into a more complete picture of customers, helping businesses move beyond knowing what people do to better understand why they do it—and anticipate what they may do next.
2. Expand insights across more people.
AI can extend trusted research methods across vastly larger populations and datasets, allowing organizations to validate ideas, uncover emerging trends, and identify opportunities with greater speed and confidence—without sacrificing rigor.
3. Put customer understanding into everyday decisions.
Insights create value only when they’re used. Instead of sitting in reports or dashboards, customer intelligence should be continuously available to the people making strategic, product, marketing, and commercial decisions. AI-powered insight agents can deliver relevant customer context at the moment decisions are made, enabling teams to act faster, with greater confidence and a stronger connection to customer needs.
Uber’s AI platform has 5K models in production, serving 10 million real-time predictions per second at peak. Uber leverages “always-on” insights and AI agents to optimize customer experience and service. The company’s first quarter of 2026 saw revenue grow by 14% to $13.2 billion with trips growing 20% year-over-year, suggesting that when insights are always-on and embedded in the product, the distance between a customer need and a business response drops to near zero.
The organizations that close the gap between insights collection and access—evolving their organizations to deploy AI as a powerful enabler of human insights —will be the ones that define the next era of consumer intelligence. Move beyond just asking what your consumers need — and start asking why they did it, what they might do next, and what you should do about it right now.
Future-Back InnovationStrategy From Category Growth to Future Markets
The biggest future growth opportunities are unlikely to sit squarely within your current category; they’re forming at the edges of it, shaped by forces most companies haven’t yet acted on. Taking share from competitors, extending product lines, entering adjacent geographies: these moves still matter. But they are increasingly insufficient to deliver uncommon growth.
The reason is structural.
CEOs spend approximately 36% of their time in reactive “firefighting” mode while devoting only 10% to 15% to long-term planning. This misalignment is exacerbated by market pressures, as 78% of financial executives admit they would reduce discretionary spending on R&D or maintenance to meet quarterly earnings targets, even if they knew it would destroy long-term value.
Consequently, the window for organizational survival is shrinking; the average lifespan of a company on the S&P 500 has dropped from 33 years in the 1960s to just 15 years today. The gap between short-term execution and long-term positioning is widening — and the companies pulling ahead are closing it deliberately.
The shift is from today’s category growth to future markets and entirely new frames of reference for the category you operate in: The imperative for future-forward growth leaders is to identify where disruption and emerging customer needs are opening entirely new markets and opportunities, and to capitalize on them with conviction. There are three critical components to understanding future markets and frames of reference that can also become an ongoing discipline within the organization:
1. Understand the drivers of change to identify future areas of demand.
Mapping the social, technological, economic, environmental, regulatory, and political forces reshaping your industry is critical, both to build an understanding of how it affects your category today and to explore emerging categories. Working deeply with subject matter experts enables growth leaders to understand the trends that define where demand is heading, not just where it sits today.
2. Define future markets and identify challenges.
An initial analysis into forces at play and demand opportunities enables growth leaders to frame future markets to dive into, mapping the competitive dynamics and customer needs.
3. Define your target destination.
Framing attractive potential markets for growth based on your business realities enables leaders to align on a target destination for sustainable business growth. With a clear picture of the business you need to become, organizations can then work backward — progressing potential business growth models through stage gates of desirability, viability, and feasibility.
Future-back innovation strategies and thinking create real friction with boards and teams focused on near-term results. But the value isn’t in the scenarios themselves — it’s in the concrete strategic bets they open to chart a sustainable and robust path to growth.
In fiscal 2018, gaming represented roughly 57% of NVIDIA’s revenue, with data centers accounting for under 20%.i NVIDIA bet early that its GPU architecture would power large-scale AI training — and committed to that destination years before the market reached critical mass. By fiscal 2026, data center revenue hit $193.7 billion — 90% of total revenue — and full-year revenue reached $215.9 billion. That transformation was the result of reading the forces of change early and building toward a future most competitors hadn’t yet recognized.
The question is not whether your category will be disrupted. It’s whether you’ll define what comes next — or arrive late to a future someone else built.
New Business Model Innovation From Products and Services to Platforms
Here’s a question most growth strategies don’t ask: what happens after the sale? For the majority of businesses, the answer is surprisingly little. The product ships, the service is delivered, and the customer relationship goes quiet until the next transaction. That silence is one of the largest untapped growth assets in business today — and the companies compounding value fastest have figured out how to fill it.
The pattern is consistent across industries: the highest-value businesses aren’t winning primarily on what they sell.
They’re winning on the depth of the relationship they maintain while customers are actively using what they’ve bought. That relationship generates proprietary data, deepens customer engagement, and creates switching costs that a lower-priced competitor simply can’t replicate. The shift is from products and services to platforms — business models that let you observe, interact with, and add value for customers during the time between one purchase and the next.
You don’t need to be a technology company. You need to create the conditions under which your business stays connected to customers during what we call the User Journey. Execution follows a four-stage progression:
1. Start with in-use visibility.
Build the ability to see what customers are actually doing with your product after the sale, which is the foundational data layer most traditional models completely lack.
2. Create interactive value.
Develop touchpoints, tools, or services that add real value during active use, deepening the customer relationship and generating behavioral signals you can learn from.
3. Personalize and grow.
Use what the platform reveals to tailor and expand the value delivered to each customer over time, which will drive increasing satisfaction and share of wallet.
4. Attract through proof.
Let the richness of the platform experience and data-validated results become a powerful acquisition tool to draw new customers through demonstrated value, not just marketing.
The biggest friction will be organizational: most businesses are structured around product sales cycles, not ongoing engagement. A platform model requires investment in data infrastructure and continuous value delivery before the financial return is fully visible.
Platform Business Model in Action: The New York Times
The New York Times evolved from a print newspaper into NYT, a multi-product digital platform — bundling news, cooking, games, audio, and sports into a single subscription. Digital-only subscription revenues grew by approximately 14% to $1.43 billion, with bundle and multi-product subscribers now representing approximately 51% of the digital base. The company didn’t grow by writing more articles — it grew by redesigning its relationship with readers across more of their daily lives.
The critical question isn’t “What new product can we launch?” It’s “How do we stay valuable to the customers we already have — and make that value visible to everyone we haven’t yet reached?”
Customer Ecosystem Management From Individual Customers to Coalitions
Most growth strategies focus on two things: acquiring more customers and keeping the ones you have. Both matter enormously. But they share a blind spot that limits how much value your business can create and capture.
The blind spot: your customers don’t exist in isolation.
Every customer is surrounded by an ecosystem of influencers, from providers to creators, advisors, and communities, who shape their decisions before, during, and after the purchase. The companies building the strongest competitive positions today aren’t just serving customers. They’re connecting the parties around them into coalitions where everyone exchanges value, and where the business sits at the center.
This is the shift from customers to customer coalitions: moving beyond a one-way value exchange between company and buyer and instead facilitating a “better together” network where participants make each other more valuable. The result: lower acquisition costs, higher lifetime value, and stickiness that a marginally better product from a competitor can’t easily break.
Executing this shift requires focusing on three areas:
1. Precision archetype scaling.
Growth in a coalition isn’t about scale for scale’s sake — it’s about the right mix of participant types: users, providers, creators, sponsors, and influencers. Identify which personas fill gaps in the ecosystem and create a self-sustaining growth loop. Are the right providers balanced to customer demand in a given market?
2. Multi-dimensional value exchange.
Look beyond the direct value your company delivers and design for the lateral value members provide to one another. When you engage the same person in multiple ways — a user who also reviews, recommends, and advocates — you drive significantly higher spend and create differentiation competitors can’t replicate.
3. Tiered ecosystem loyalty.
Move from transactional discounts to recognition systems that reward specific behaviors — quality, consistency, responsiveness — rather than just volume. This lets you capture premium needs at higher margins while remaining accessible at the entry level.
The friction here is real. Investing in peripheral ecosystem participants can feel indirect when teams are measured on near-term revenue. But the payoff is a self-reinforcing system that compounds over time.
Airbnb’s competitive advantage isn’t inventory — it’s the coalition. Guests rely on reviews, host interactions, and experience recommendations when deciding where to stay. Approximately 41% of U.S. hosts qualify as Superhosts, earning at least 29% more than standard hosts — a tiered recognition system that incentivizes quality, raises satisfaction, and drives the reviews that attract more guests. Beyond hosts, Airbnb builds a customer coalition by engaging creators and local communities to share authentic experiences, creating a network of advocates who drive trust and influence through their own voices and networks. That self-reinforcing loop helped Airbnb reach $12.2 billion in FY2025 revenue with 533 million nights and experiences booked — built not on a better product alone, but on a coalition that compounds value for every participant.
The question isn’t just “How do we serve our customers better?” It’s “Who are the parties around our customers that make the experience better — and how do we bring them together?”
Organizational Culture as Catalyst From Stated Values to Purpose-Built Culture
Every organization has written its values on a slide or poster. Very few have a culture that accelerates growth. The gap between what a company says it believes and how people inside it behave is where most growth strategies quietly die.
The evidence is consistent: research shows that approximately 70% of digital transformations fall short of their objectives.
The failure is rarely due to a flawed strategy or insufficient funding. Instead, it is most often rooted in organizational and cultural resistance — the antibodies within an organization that reject the very changes leaders are trying to implement. You can invest in the sharpest strategy and the most advanced tools, but if the culture isn’t built to absorb and act on them, the organization will default to what it already knows.
The shift is from stated values to purpose-built culture: a culture deliberately designed to champion bold bets, move with speed, and sustain momentum long after the initial energy of a new initiative fades. This isn’t about writing better values statements. It’s about rewiring how the organization operates.
Organizational Ambition
Defining a compelling ambition for the organization aligning purpose, strategy and culture — enabled by the right behaviors
Leadership Enablement
Clarifying what is expected of leaders, providing them with the skills and tools to demonstrate change and build trust with their teams
Employee Ignition
Sparking employee interest, passion, and accountability by showing them what great looks like
Executional Excellence
Unlocking people and work through systemic change in service of delivery against strategic objectives
Three moves make this real:
1. Decentralize growth ownership.
Uncommon growth cannot be a top-down mandate. Empower people at every level to identify and act on opportunities — and to challenge legacy processes that slow the organization down. When growth ownership is distributed, the company becomes a network of sensors rather than a hierarchy waiting for direction.
2. Operationalize experimentation.
Move beyond “permission to fail” toward active incentives to experiment. Reward the process of discovery, not just the outcome. If your performance reviews only recognize hitting quarterly targets on legacy products, the culture will never champion the new — no matter what the values slide says.
3. Build momentum loops.
Shift from annual planning to rolling cycles that redirect resources toward what’s working in real time. Leaders must move from managing performance to evangelizing the behaviors that produced it.
The tension is real: protecting the core business while funding the future creates friction. Culture must provide the permission to reconsider your own business when the evidence points forward — and the resilience to sustain speed without burning people out.
Organizational Culture as Competitive Advantage in Action: e.l.f. Beauty
e.l.f. marked its 29th consecutive quarter of net sales growth and market share gains, with net sales of $1.63 billion for fiscal year 2026, an increase of 25%. The company’s willingness to experiment with emerging platforms — it was one of the first beauty brands on TikTok and has since expanded to Roblox and Twitch — reflects a cultural DNA that rewards speed and experimentation over perfection. That consistency isn’t a single product hit — it’s a culture that moves at what e.l.f. calls “e.l.f. speed,” where purpose and performance reinforce each other daily.
You cannot program growth into a spreadsheet. You need a human-centered transformation model and a culture supportive of change, which can only come about through nurturing people — and cultivating the systems, skills, incentives, and norms that shape how they show up every day.
The journey to creating Uncommon Growth starts today.
Every growth move describes a shift that successful Uncommon Growth companies have already made — and that their competitors, in most cases, have not. The distance between those two groups is widening. Not because companies lack talent or capital, but because they’re still running plays designed for a world that no longer exists. None of these plays require you to rebuild your company from scratch, but each one requires you to challenge an assumption your organization has been operating on for years. The companies achieving uncommon growth aren’t waiting for perfect conditions. They’re building the capability to grow without them.
The playbook is here.The question is what you do next.
Prophet’s Uncommon Growth Playbook and practice areas are led by a multidisciplinary team of experienced growth leaders across strategy, insights, innovation, experience, and AI solutions—all with an eye on speed to impact.
Contact us below to learn more.
Thank you for your inquiry.
If your submission requires a response, we will be in touch shortly. In the meantime, we encourage you to learn more about our firm and read some of our latest and greatest thinking.
Authors
Mike Leiser Chief Transformation Officer, Senior Partner
Jay Milliken Global Lead of Growth Strategy, Senior Partner
The Retail Store as a Platform: Designing for Commerce, Curation, Connection, and Culture
The most forward-thinking retailers are engineering immersive, multi-faceted platforms that curate commerce, foster human connection, and cultivate culture.
For decades, the narrative surrounding physical retail has been one of disruption and decline, a story pitting brick-and-mortar against the digital juggernaut of e-commerce. But this binary view is obsolete.
The future of retail isn’t about the store versus the website; it’s about the store acting like a website—or more precisely, like a platform.
The most forward-thinking retailers are no longer just designing places to transact; they are engineering immersive, multi-faceted platforms that curate commerce, foster human connection, and cultivate culture.
Why a Platform?
To understand this shift, we must first dissect what a platform business truly is. Unlike traditional linear businesses that create value in a straight line (make a product, sell it to a customer), platform businesses create value by facilitating interactions and transactions between distinct, interdependent groups. Think of Uber (connecting drivers and riders), Airbnb (connecting hosts and guests), or the Apple App Store (connecting developers and users).
Their core asset is not inventory, but the ecosystem and the data that flows through it.
They thrive on network effects: the more participants on one side, the more valuable the platform becomes to the other.
So, how does a physical retail store transform into this kind of dynamic platform?
It ceases to be a mere point-of-sale and becomes a curated, multi-faceted ecosystem where the retailer acts as the orchestrator, not just the owner.
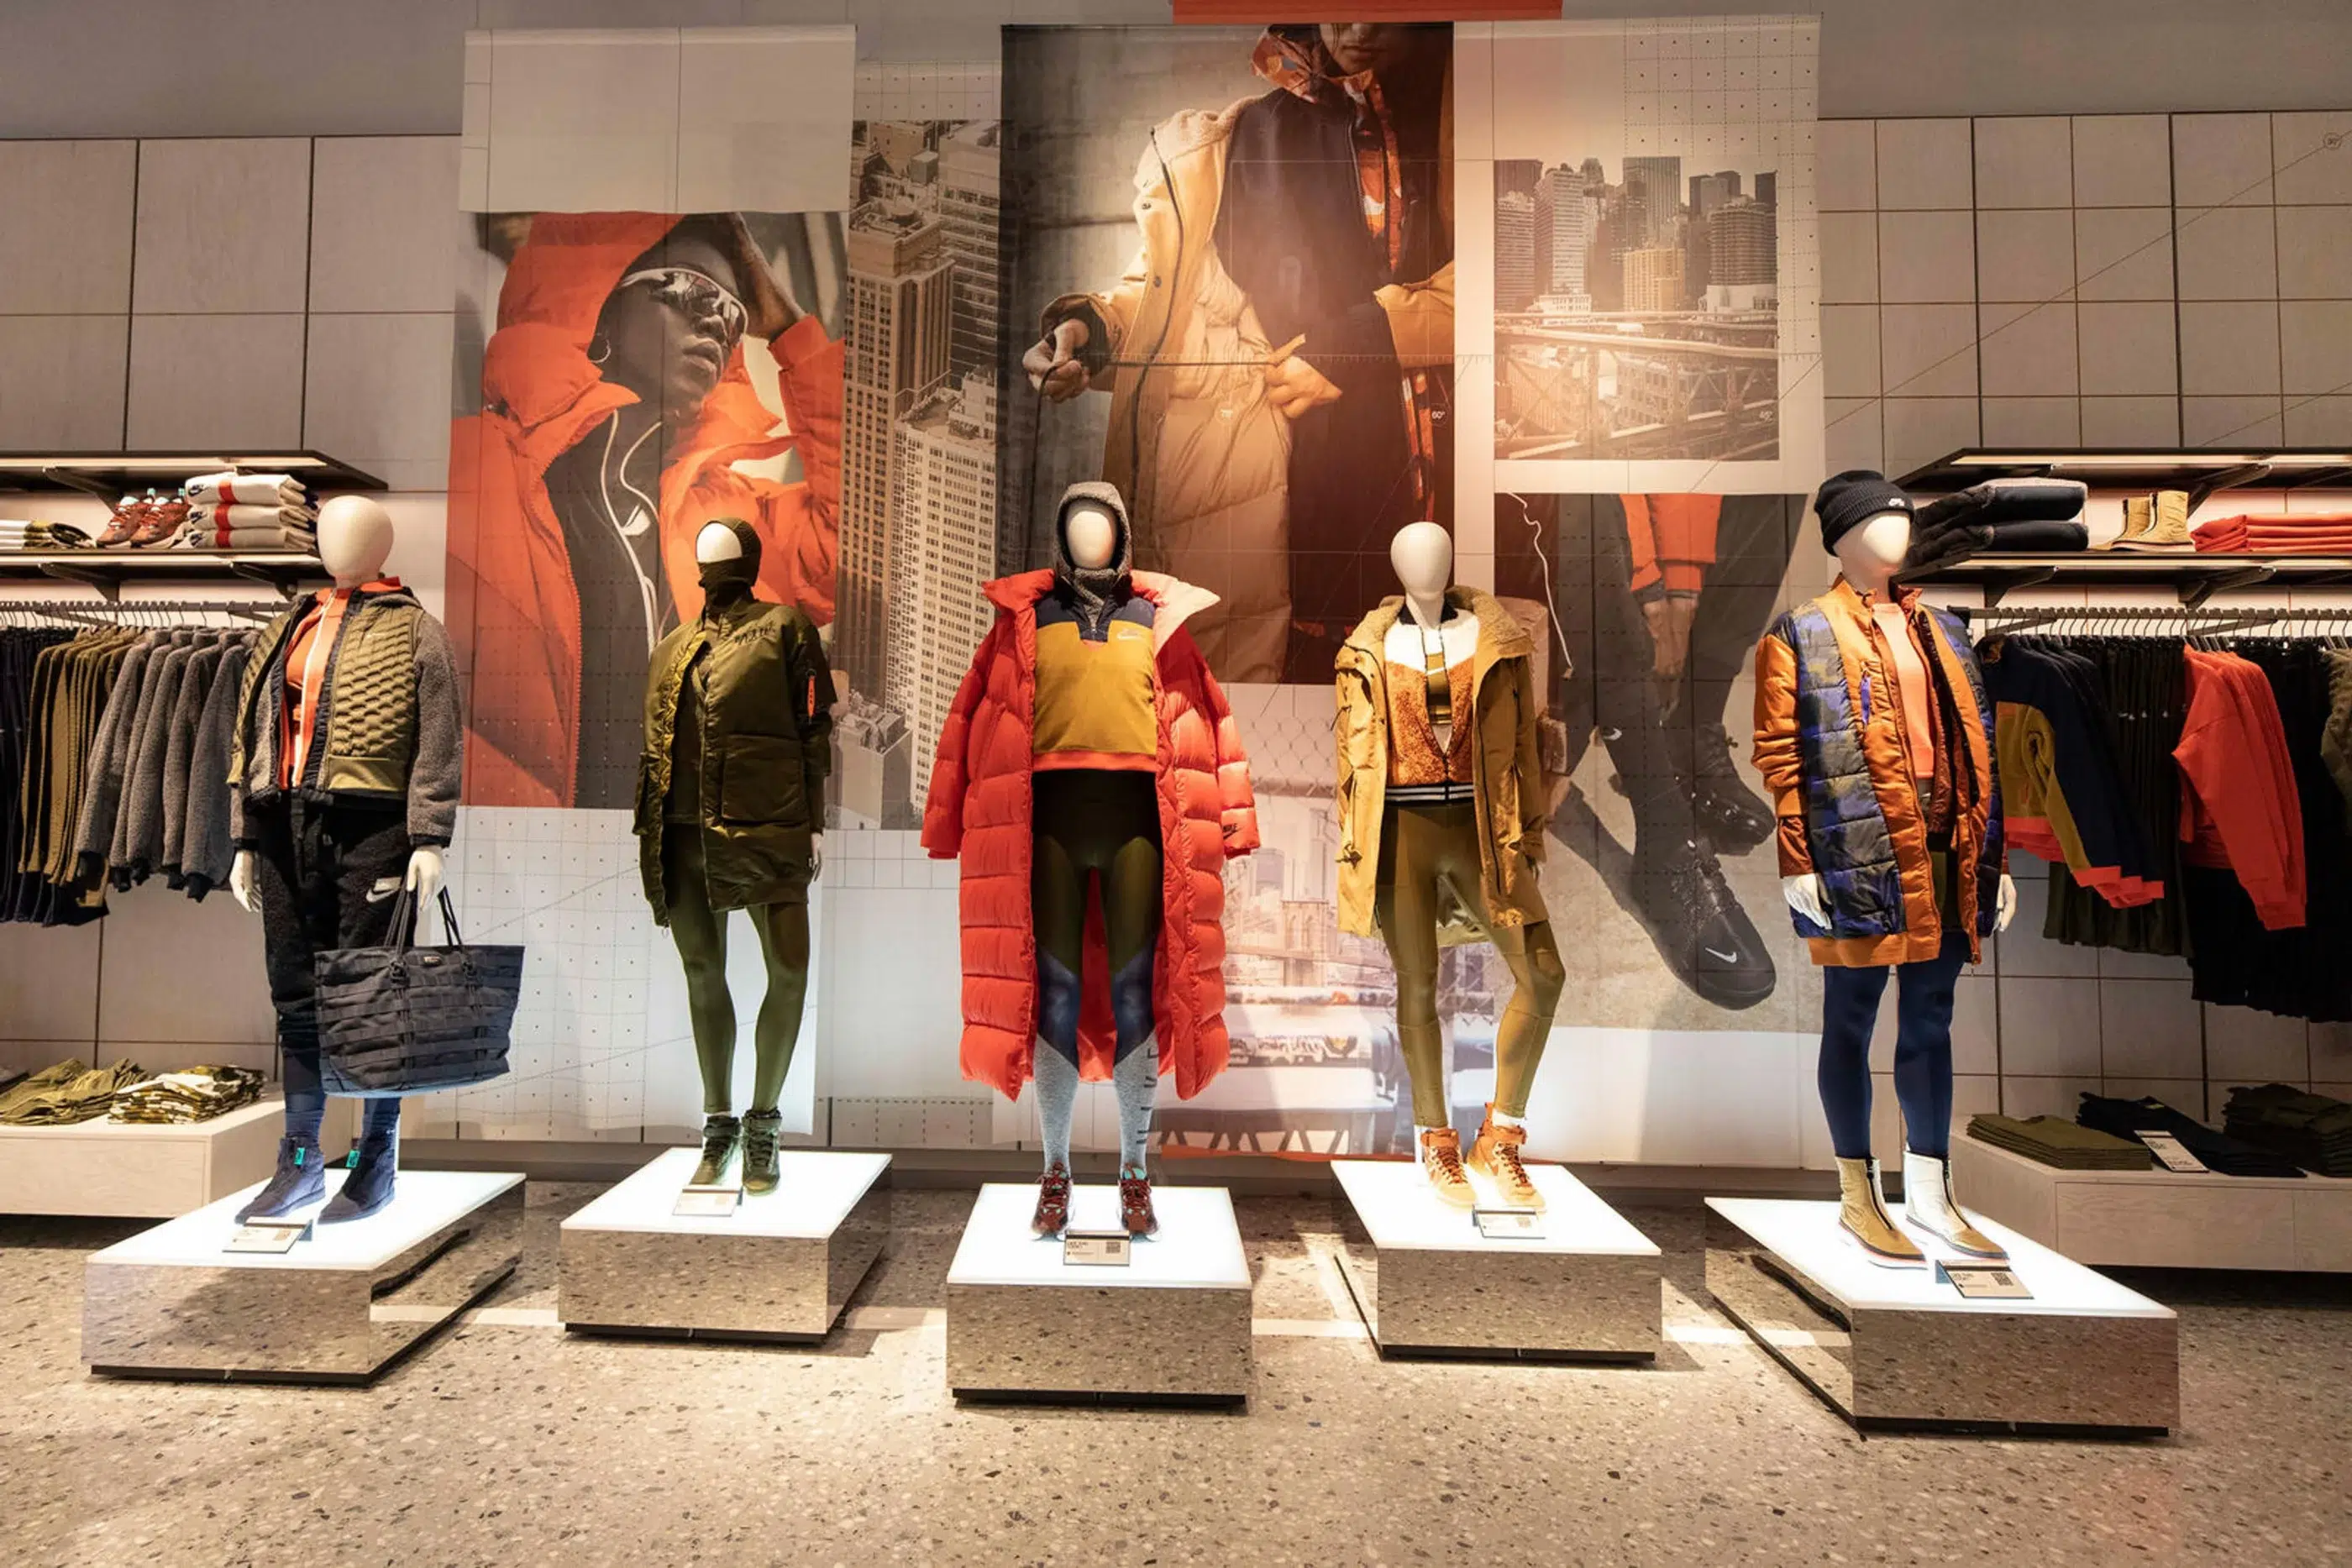
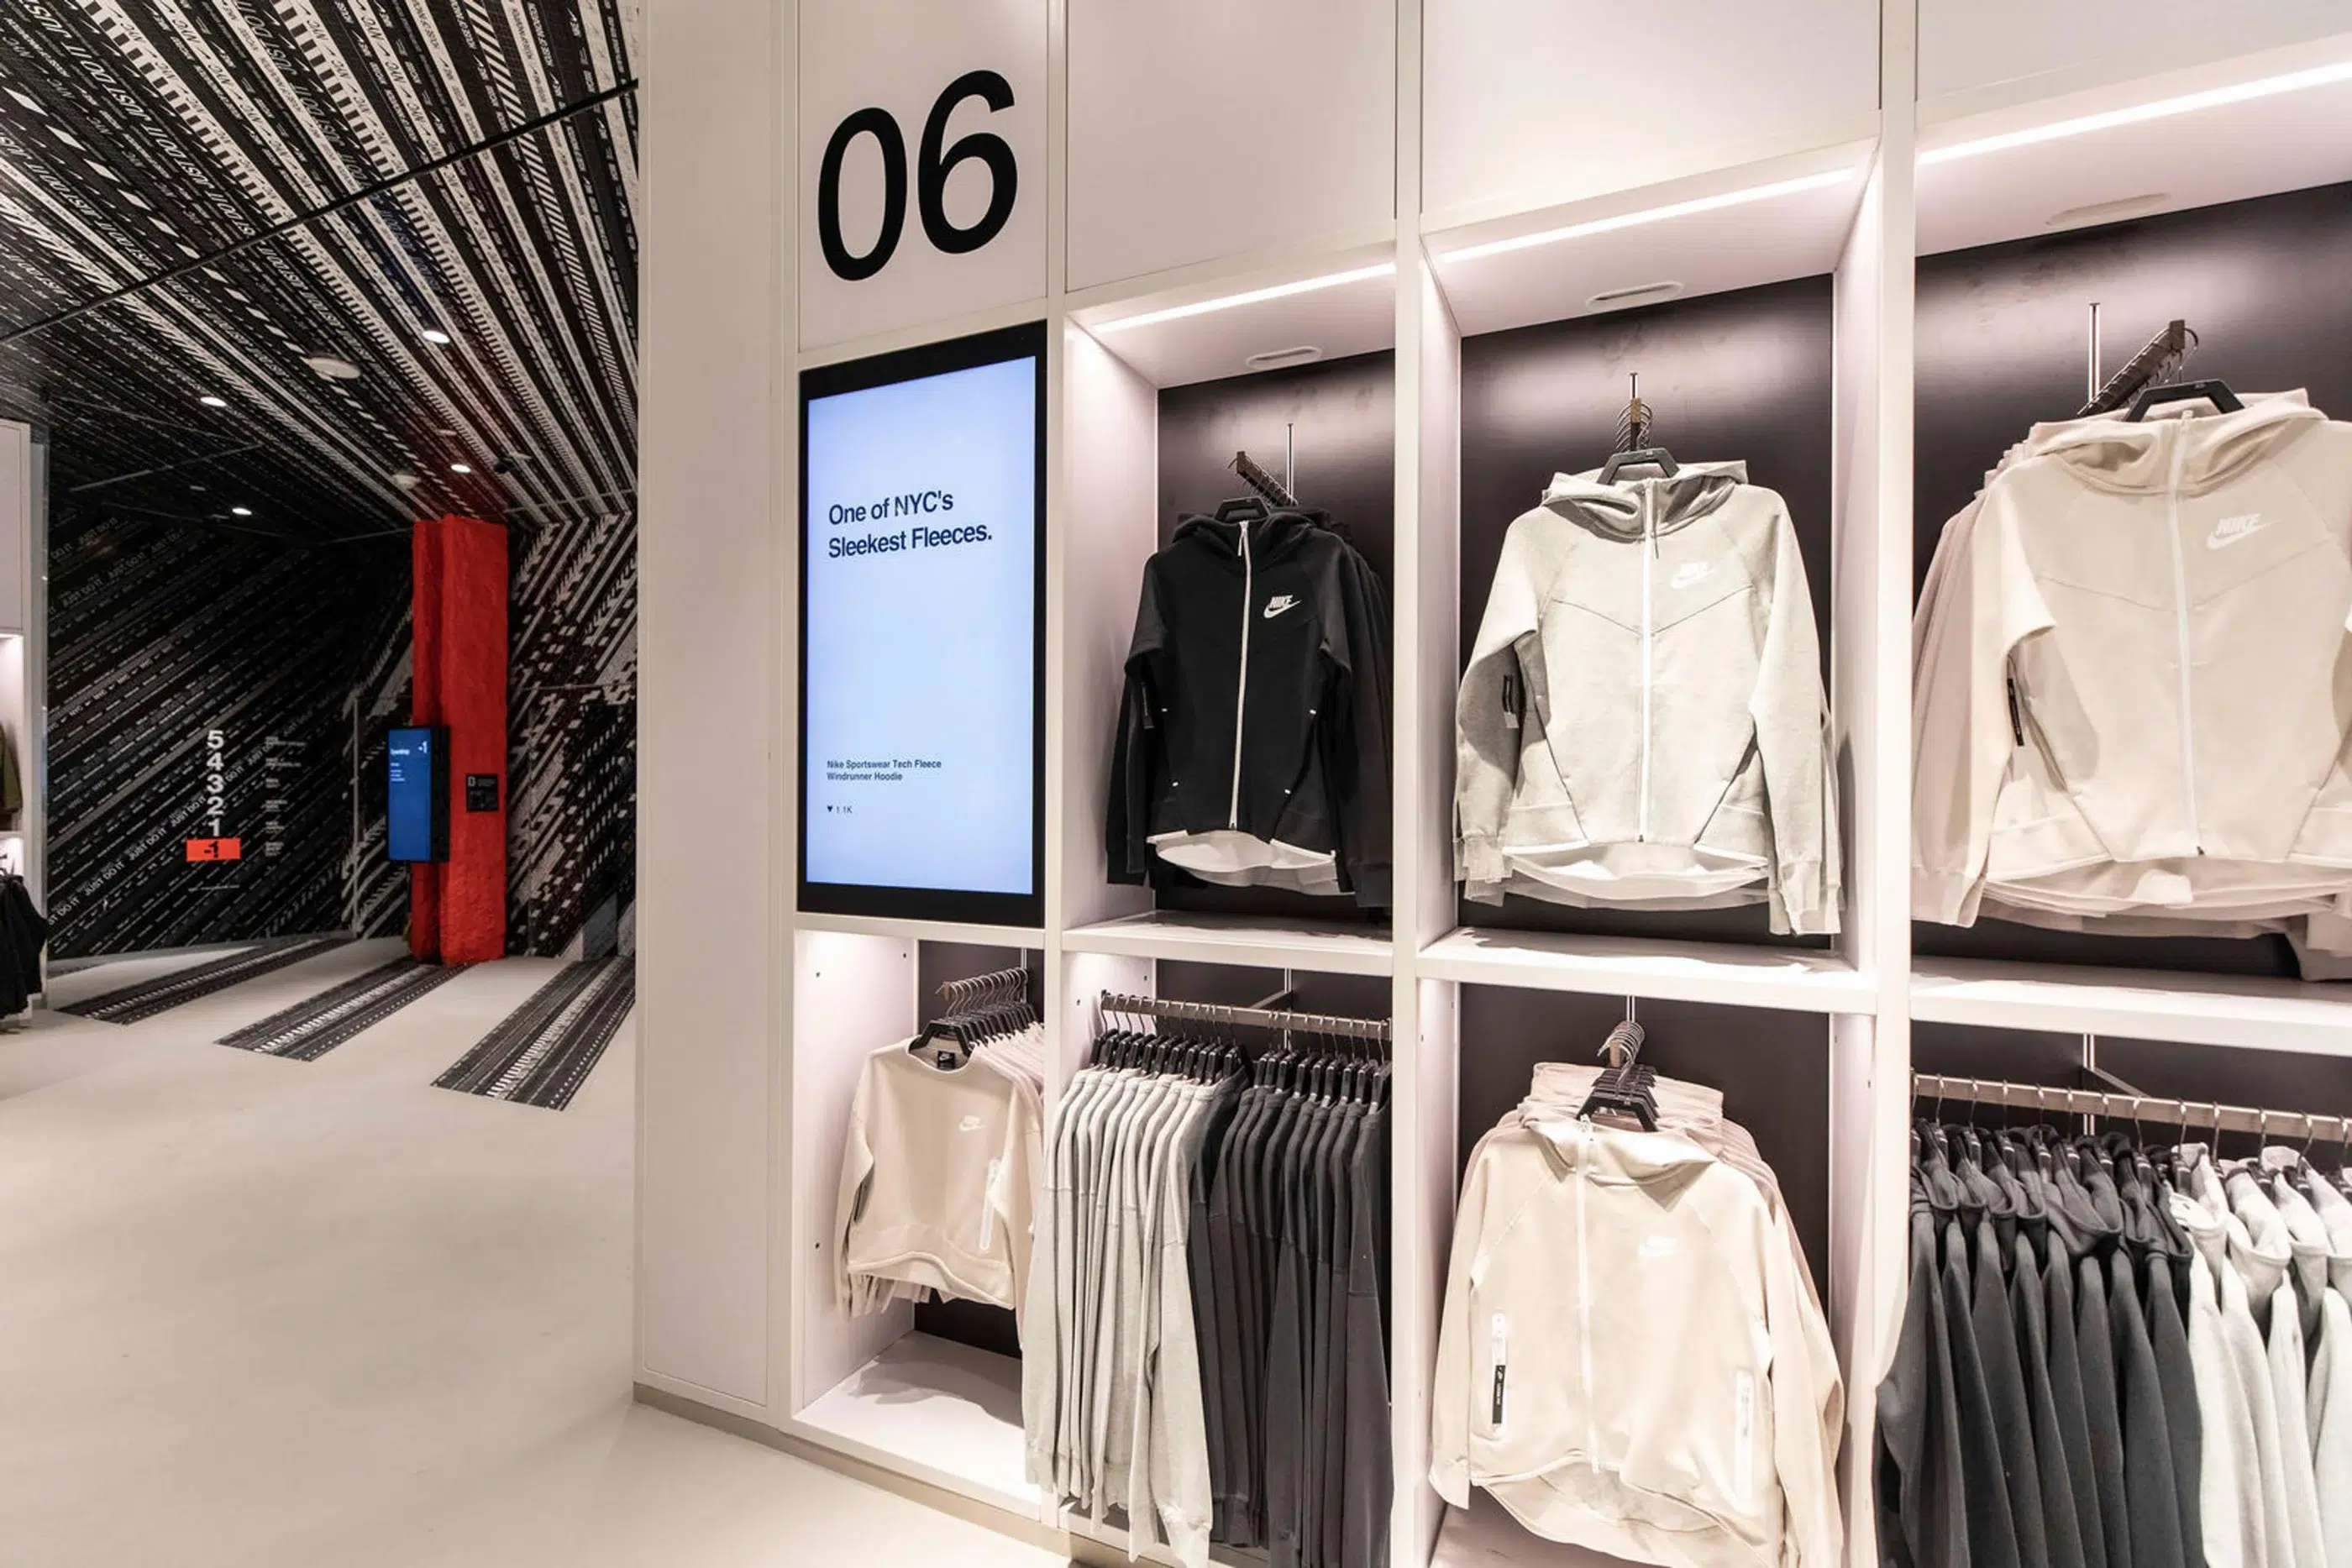
Currently, only a handful of retailers operate stores with this mindset; some fashion brand houses and others like South Korea’s Gentle Monster, Nike’s House of Innovation, and Starbucks Reserve Roastery locations come close. So, how can other retailers turn physical stores into dynamic platforms?
Gentle Monster, Shanghai flagship; art and technology meet fashion and beauty (Source: Gentle Monster) Gentle Monster, Shanghai flagship; art and technology meet fashion and beauty (Source: Gentle Monster)
A full customization wing lives in The Arena, delivering on Nike’s pioneering DIY spirit. (Source: Nike)The latest selection is continually rotated throughout the store. (Source: Nike)With Shop The Look, customers can scan the code at the foot of a mannequin and shop the entire outfit, which can then be purchased immediately through Instant Checkout. (Source: Nike)The Nike Speed Shop uses local data to stock its shelves, and re-stock them based on what the community wants. (Source: Nike)
Starbucks Reserve, Tokyo Roastery (Source: Starbucks)
The Store as a Platform for Curated Commerce
In a traditional model, commerce is straightforward: the retailer stocks what it predicts will sell. The platform store, however, reimagines the floor as a dynamic marketplace.
This means inviting third-party brands, both digital natives and local artisans, to “plug in” to the physical space. These brands become the “producers” on the platform.
For example, a Target or a Nordstrom isn’t just selling its own inventory; it’s hosting a rotating cast of pop-ups and exclusive collaborations. The physical store can become a living, breathing showroom for DTC (Direct-to-Consumer) or new-to-market brands seeking tangible customer touchpoints, and for established brands to test new concepts, as well as the in-store media promoting store-brands and those of the partners or suppliers.
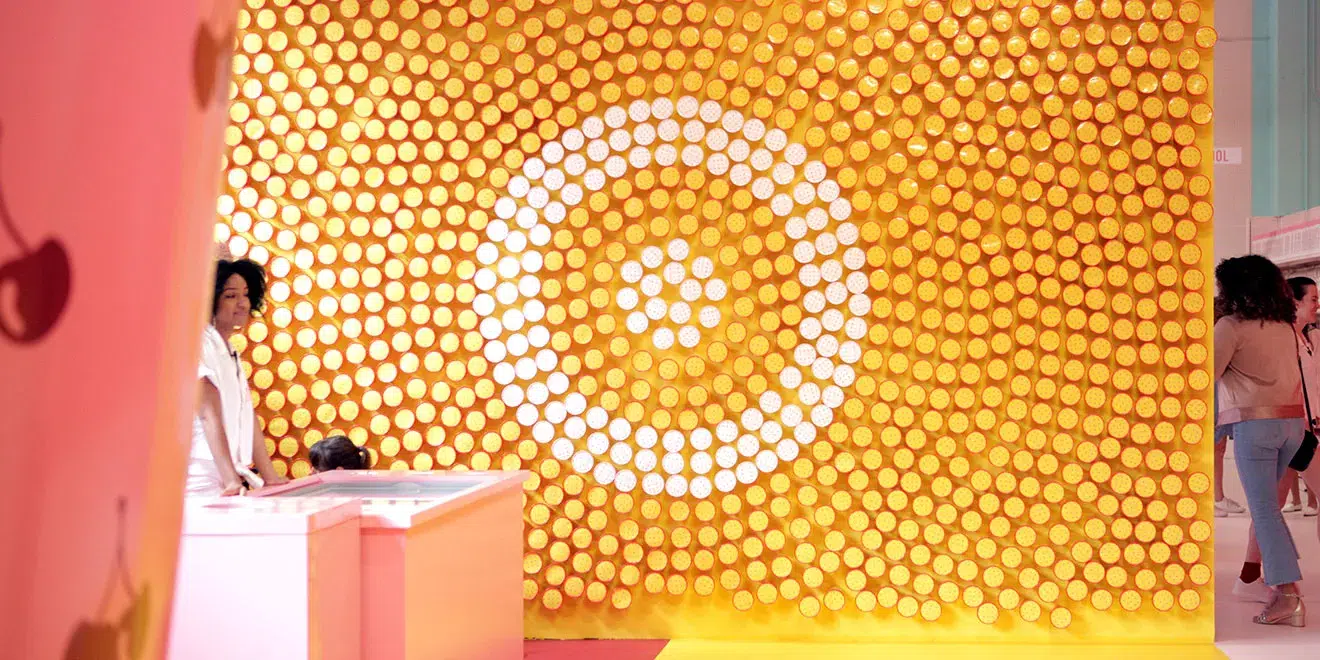
Target partnered with Museum of Ice Cream to launch a pop-up shop in NYC (Source: Yuliya Kim for Adweek)
Over the years, Target has launched dozens of shop-in-shop partnerships with brands and designers to expand its relevance, driving traffic and revenue in important categories.
The retailer’s role shifts from dictator of assortment to curator of experience. They provide the stage—the prime real estate, the logistics, the foot traffic—and take a fee or revenue share from sales.
This model can de-risk inventory, ensure a constantly refreshed and novel assortment, and turn the store into a destination for discovery, not just routine replenishment.
The commerce becomes a value-added service within a larger experience.
And this new curated commerce is supported by both digital tools allowing more seamless online-offline integration.
Collaborations Context:
The store becomes a vessel of collaboration with other culturally relevant brands or personalities, but in the context of the store’s brand experience. The immersive aspect blurs the line between the partner’s equities and the store’s brand, creating an exciting “equity flow” between the parties that can be felt by the customer, shaping brand memories that drive future visits.
Seasonal Sensations:
Shifts in visual merchandising are not just about decorating for the season but being relevant to the consumer mindset regarding everything else going on in their lives. The “platform” shifts its language, its visual effects, and particularly its in-store media content, messaging, creative, and promotions to align with consumer attention.
The Store as a Platform for Human Connection
This is where the physical platform truly outshines its digital counterparts. E-commerce can be transactional and solitary.
The store-as-platform is designed for social and educational interaction, creating a powerful network effect between customers, staff, and brands.
The “users” on this side of the platform are the customers seeking connection and knowledge.
The “providers” are the store’s staff, brand ambassadors, and even fellow shoppers.
Staff as APIs:
In a platform store, associates are not just cashiers or stockers; they are “Application Programming Interfaces” (APIs)—human endpoints of data and expertise. Armed with AI-enabled tablets that access real-time inventory, customer purchase history, and product information, they can offer hyper-personalized service. They are stylists, tech gurus, and guides who facilitate a deeper relationship between the customer and the brand ecosystem.
The “platform” also leverages digital tools to supplement the store staff, such as “endless aisles” providing vastly expanded assortments with minimal inventory carry, and visualization tools (magic mirrors and mobile-enabled AR applications) to streamline trial supported by the personal guidance of staff.
Nordstrom store associate with tablet (Source: Nordstrom)
The next generation of “clienteling” will be AI-enabled.
Community as Content:
The store itself becomes a venue for events—workshops, maker classes, fitness sessions, or panels. A REI store hosting outdoor survival classes or an Apple store holding Today at Apple creative sessions aren’t just selling products; they are selling proficiency, passion, and community.
These events create recurring reasons to visit, transforming the store from a shop into a clubhouse. The connections formed here—between customer and expert, and between customer and customer—create immense loyalty and a defensible moat that Amazon cannot easily replicate.
REI indoor photo of class or activity (Source: REI)
Building community programming around shared interest drives trips and loyalty.
The Store is the Clubhouse:
As loyalty programsevolve to be more about access to experiences and not just collecting points, the store environment can play a key role in evoking a sense of belonging.
Location-based programming as described above is only the start, as technology unlocks better forms of recognition (opt-in facial recognition and geo-location using signals from mobile devices–or even using simple card swipes or RFID readers), more personalized attention can be brought to loyalty program participants, rewarding frequent visits with in-the-moment promotions, access to preferred store hours, and even the provision of food and beverage amenities…
Not by Bread Alone:
As noted above, in creating a platform orientation to the store, the execution should at a minimum deliver a “more reasons to go and more things to do when you are there” experience. Food and beverage offerings provide that always-appreciated and often-desired complement to a shopping trip.
Aligning the offer and assortment with the brand’s personality (think Ralph’s, the Ralph Lauren café attached to many of its stores globally), and should be tuned to be feasibly operated.
Ralph’s Coffee café at Shaw Centre, Singapore; Ralph Lauren setting up coffee shops adjacent to its stores. (Source: Grazia)
The Store as a Platform for Cultural Cultivation
The highest function of the retail platform is to move beyond utility and into identity. It becomes a stage for cultivating and broadcasting a specific culture. Platforms like Instagram or TikTok don’t just host content; they shape trends, language, and aesthetics.
Similarly, a retail store can act as a cultural touchpoint. It’s a three-dimensional manifestation of a brand’s worldview.
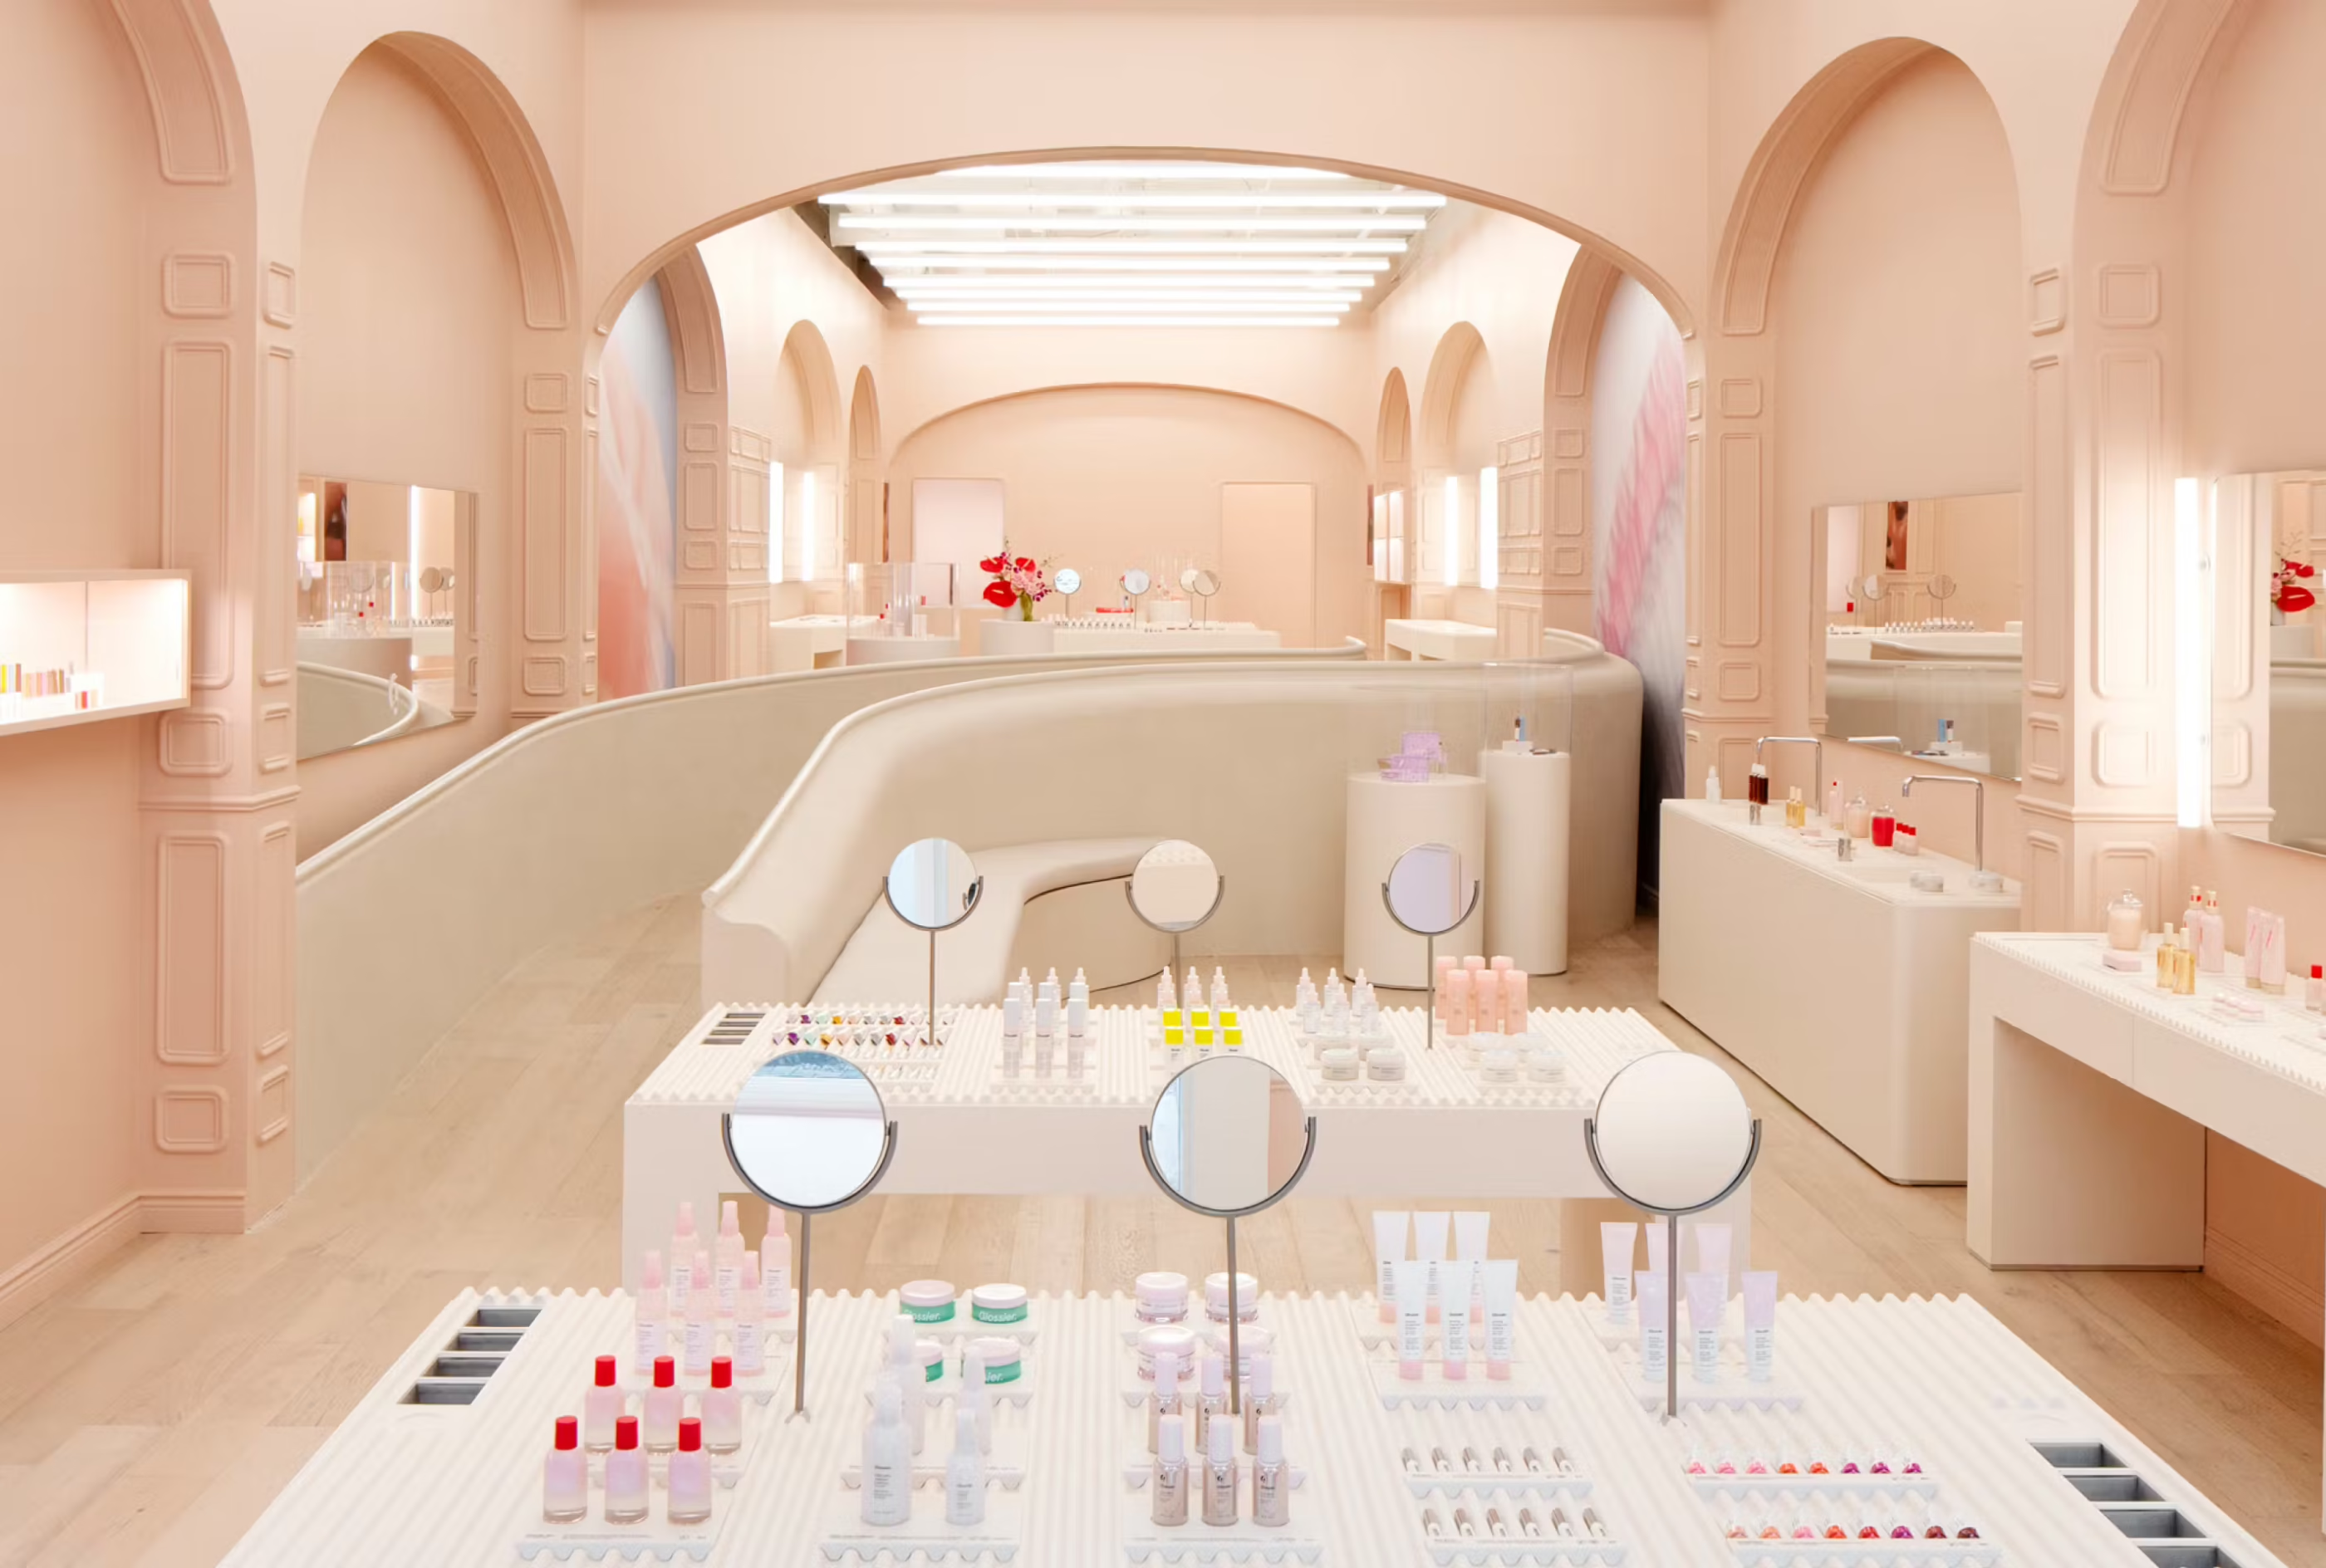
A Glossier store isn’t just a place to buy makeup; it’s an Instagram-ready shrine to millennial-pink aesthetics and community-driven beauty. A Patagonia store isn’t just for outdoor gear; it’s a hub for environmental activism, complete with repair workshops and advocacy materials.
In this model, the transaction is almost a byproduct of cultural participation.
Consumers, especially younger generations, don’t just buy products; they buy into beliefs. The retail platform allows them to physically immerse themselves in those beliefs.
The store curates not just products, but a vibe, a value system, and a tribe. This cultural capital is the most powerful form of branding, creating evangelists who wear their purchases as badges of affiliation.
Glossier Philadelphia (Source: Glossier) Glossier District of Columbia (Source: Glossier) Glossier store with customers taking Instagram photos (Source: BoF)
Being in the cultural conversation drives targeted relevance.
The Store as a Media Platform
In today’s retail environment, the store itself is being reimagined as a dynamic media channel, where digital screens transform passive aisles into immersive content experiences. Gone are the days of simple promotional loops; these networks now deliver curated, high-quality content ranging from brand storytelling and recipe tutorials to lifestyle documentaries and live social media feeds.
This content serves a dual purpose: it captivates customers, increasing dwell time and enhancing brand perception, while simultaneously functioning as a highly targeted, daypart-driven advertising platform.
Brands can purchase screen time much like a digital out-of-home network, delivering contextually relevant messages at the precise moment of purchase consideration, effectively turning the physical store into a broadcast studio for targeted, shopper-centric media.
This evolution into a media platform allows retailers to monetize their physical footprint and customer attention in new ways, generating high-margin revenue streams beyond product sales.
The data captured—such as dwell times, engagement metrics, and correlation with sales data—creates a powerful feedback loop, enabling both retailers and brands to refine messaging in real-time for maximum impact.
Ultimately, the store-as-media-platform model elevates the shopping journey from a mere transaction to an engaging, informative, and entertaining experience.
It represents a profound convergence of physical and digital worlds, where the environment not only sells products but also tells stories, builds community, and operates as a sophisticated, measurable media entity in its own right.
Store endcaps fitted with screens (Source: AdAge)
POS media can drive disproportionate selection opportunities for brands and a meaningful revenue stream for the retailer.
Designing the Platform: Data as the Foundation
Underpinning all four of these dimensions—Commerce, Curation, Connection, and Culture—is data. A platform is useless without a feedback loop. In-store sensors, Wi-Fi analytics, mobile app interactions, and transaction data provide a rich, nuanced understanding of how people move, dwell, and interact within the physical space.
This data informs everything: which pop-up brands drive the most footfall, which workshops lead to the highest basket size, which product placements create the most social media buzz, and even how loyalty can be manifested in the store.
This allows retailers to iterate and optimize the “user experience” of their physical platform with the same agility (but perhaps not the same speed) as a digital product team.
This closed-loop system ensures the store remains relevant, responsive, resilient…and productive.
Hema Market uses data to track freshness and food safety information, ensure in-stocks on popular items and manage 30-minute delivery windows for in-store purchases. (Source: Freshippo)
Hema Market leverages its fully integrated online-to-offline data ecosystem to deliver a seamless, hyper-personalized customer experience. It unifies digital and physical shopping, enabling real-time analysis of individual preferences, purchase history, and even dwell time.
This data powers dynamic in-store digital signage and an AI-driven replenishment system, ensuring popular SKUs are never out of stock. The result is a frictionless journey where customers receive relevant offers, enjoy accurate 30-minute delivery windows predicted from historical traffic and order data, and find stores curated to their neighborhood’s tastes—transforming raw data into intuitive, time-saving convenience.
The Transaction as an Outcome, Not the Goal
The store of the future is not a warehouse. It is a networked platform. Its success is measured not just in sales per square foot, but in engagement per visit, the strength of its partner ecosystem, and its cultural resonance.
By designing for commerce as a curated service, for connection as a core utility, and for culture as a key differentiator, retailers can build physical spaces that are not just surviving the digital age but thriving within it. The transaction is no longer the singular goal of the store visit; it is the natural outcome of a valuable and valued platform experience.
Retail’s next chapter will be written by stores that function as platforms — shaping commerce, curation, connection, and culture, with the transaction as the outcome rather than the aim.
Prophet helps retailers design these experiences to deepen relevance, loyalty, and drive uncommon growth.
Luxury in Germany is becoming less about dreaming big and more about feeling safe. After years of economic instability, global conflict, and social strain, German consumers are recalibrating what “luxury” really means.
These insights come from Prophet’s latest Consumer Generation Premium and Luxury Study, based on a survey of 1,000 German consumers spanning Gen Z through Baby Boomers. First launched in 2018 and now conducted for the fifth time, the research explores shared patterns and generational differences across values, luxury perceptions, brand and product expectations, buyer journeys, purchasing behavior (including AI), and, of course, the implications for business.
Since we began studying this market, the shift has become unmistakable. What once centered on material ambition has steadily given way, across generations, to a desire for reassurance. In 2026, stability now outweighs status and upward mobility, with financial independence, relationships, and health defining what premium truly means.
One explanation is that in an era of heightened uncertainty, consumers are retreating toward what they can physically own, control, and secure.
According to Jörg Meurer, Partner at Prophet, “The current data is heavily influenced by a “poly-crisis” environment, including economic uncertainty, global conflict and political instability. These macro-factors are now directly reflected in consumer sentiment and core values.”
This shift is most visible among Millennials. Once seen as the generation driving cultural and economic change, they now show broad fatigue. Nearly every value and life priority dimension has weakened, suggesting mounting pressure, overload, and disillusionment rather than confidence or momentum.
Gen Z shows a different but equally telling shift, stepping back from activism and traditional success. While their core idealism remains intact, many feel caught between strong values and a growing sense of powerlessness to effect real change in an increasingly volatile world. Instead, more are turning inward, placing greater emphasis on personal meaning and belief systems, including religion. This signals a move from trying to change the world to trying to understand it.
Baby Boomers, by contrast, remain the most stable cohort. They continue to value heritage brands, high‑end service, and familiar luxury codes, while maintaining relatively strong environmental and sustainability beliefs. In a volatile environment, they are the segment most anchored in continuity.
While luxury brands still attract consumers, loyalty is weakening. Across generations, brands remain important reference points, yet only Baby Boomers stay truly loyal. Buyers are more selective and cautious: quality, durability, functionality, design, and great service still matter, but expectations are lower than in the past.
At the same time, premium customers are questioning price markups for image and emotion, becoming more price‑sensitive. Interestingly, visible logos and statement luxury are making a comeback, with fewer purchases being made, but each one obviously carrying more symbolic weight.
According to Meurer, “As expected, AI is transforming every stage of the luxury buying journey and is not just a “youth play” but also widely adopted by older generations, such as the growing willingness across all generations to let AI agents make purchasing decisions.”
For brands at the premium end of the market, there are profound implications with regard to brand management and their go-to-market strategy.
Reassurance beats aspiration: Consumers aren’t looking to be dazzled. They want brands they can trust, that feel stable, clear, and genuinely useful.
No one‑size‑fits‑all consumer: Growth requires sharper segmentation: Gen Z seeks purpose and agency, Millennials want convenience and relief, and Boomers value recognition and reliability.
Brands must prove relevance, not just heritage: Brand equity still matters, but history alone doesn’t sell. Luxury brands must turn their promise into clear performance, problem‑solving, and everyday relevance.
Practical value defines modern luxury: Convenience, wellbeing, and service now drive premium appeal. Saving time, reducing complexity, and delivering comfort through high‑touch (often AI‑enabled) service increasingly shape buying decisions.
Technology must be useful and credible: Consumers expect tech to solve real problems, not just impress with innovation.
Convenience is the new luxury – wellbeing is the business: Convenience-led products and services that save time and reduce complexity, while enhancing physical and emotional wellbeing, are becoming the defining expression of luxury for a new generation of consumers.
The same logic applies to employer brands: In a climate of crisis fatigue, employer attractiveness is increasingly defined by stability, purpose, development opportunities, and psychological safety. Reassurance a core value proposition not only for customers, but for talent as well.
Luxury is entering a reassurance era, where trust, usefulness, and stability matter more than spectacle or status. Brands that adapt to this shift, across generations, channels, and technologies, will be best positioned to stay relevant in uncertain times.
Four areas that shape merger and acquisition value creation.
Despite growth being the primary rationale behind most merger and acquisition (M&A) deals, too often, transactions close without creating a stronger business. Harvard Business Review estimates that 70–90% of deals fail to realize their intended value.
Recent Prophet research offers a useful lens on why. We analyzed the S&P Composite 1500 and identified 179 companies that outperformed their industries by delivering exceptional, sustained growth between 2019 and 2024.
On average, these companies delivered 27% annual revenue growth, compared with 6% for others. We then looked more closely at the Uncommon Growth companies that were active in M&A, alongside major transactions in the past five years, to identify the choices that distinguish stronger performers.
The differentiator is rarely the deal itself, but what companies do after the strategy is set. Top performers move beyond treating M&A as a financial event, using it instead to build a business that is more relevant, more capable, and better positioned than either company alone.
1. They Articulate the Story of Value Early – and Create Immediate Narrative Clarity for Investors, Employees and Customers
M&A winners give the market a clear reason to care, articulating early a concise story of value that explains why the deal happened, what it unlocks, and how it will make the combined business more compelling. The strongest stories are not abstract or purely financial; they specify the core capability, adjacency, or platform advantage the transaction is meant to create.
This clarity provides investors with a basis for belief, helps employees understand what is being built, and equips commercial teams to talk about additive value that the deal creates with prospects and customers. When the value story is vague or overly technical, attention quickly shifts to back-end mechanics while the growth case remains unclear.
In some of the strongest cases, M&A did more than add capabilities or revenue. It helped shift the company’s frame of reference in the market. For example, Xylem used the Evoqua acquisition to move from being seen more narrowly as an equipment and infrastructure player toward a broader water technology, treatment and services platform with stronger recurring-revenue characteristics. Nasdaq used Adenza to reinforce its shift from market operator toward a higher growth, more software and solutions-led financial technology and infrastructure business. In both cases, the deal supported a stronger investor narrative around quality of growth, business mix and margin potential.
2. They Define and Actively Manage Brand Portfolio and Architecture Logic
Ambiguous brand portfolios create friction by confusing customers, diluting commercial focus, duplicating investment, and slowing execution.
M&A winners are deliberate from the outset about brand portfolio and architecture: which brands to integrate, which to keep distinct, and the role each should play in supporting growth. They do not leave these questions unresolved or assume they can be addressed later. When managed well, brand architecture clarifies the offer, helps leadership prioritize investment, and gives the organization a disciplined path for building, combining, or retiring brands over time. Importantly, they also treat brand architecture as a living system, to be actively managed as the business evolves and priorities shift.
Our research shows that top performers made these choices explicit and followed through. Home Depot preserved the SRS brand and operating model, which delivered $6.4B in fiscal 2024 sales. Extra Space, by contrast, consolidated under one brand after concluding dual brands lacked payoff. UBS made the clearest call, retiring Credit Suisse entirely. The common thread is not one brand versus many, but early, deliberate choice and sustained execution.
3. They Treat Brand as an Operating System, not Just a Communications Asset
The best M&As do not treat brand as a late-stage communications wrapper. Rather, brand functions as an operating system: the organizing idea that connects business ambition, market confidence, and internal alignment. It defines what the combined company stands for, how it creates value, and how decisions should be made—across client engagement, sales, talent, partnerships, and leadership behavior.
Used this way, brand shapes integration rather than decorating it. It guides how the business is integrated, how the new company is perceived, investment decisions, and can inspire confidence. Done well; it turns a transaction into more than a legal or financial event, providing a unifying logic that supports execution and growth.
Our research shows that top performers used brand to drive growth. Carrier positioned Viessmann as a premier brand and platform in sustainable climate solutions. UBS applied the same principle at far greater complexity when migrating Credit Suisse, using a clear brand narrative, “Banking is our Craft” to reinforce reputation, retain and grow client assets.
4. They Strategically Align Culture and Performance
Culture is one of the clearest differentiators between deals that build momentum and those that stall. While hard to measure in a short financial window, its effects surface quickly. When leadership is unclear or behaviors misaligned, value creation slows. When leadership creates a post‑deal environment that is coherent, purposeful, and well led, the organization can forge ahead.
Culture should not be treated as a soft topic or parallel workstream, rather a catalyst for success. Leaders define the values, behaviors, and ways of working that guide the combined company, shaping collaboration, decisions, and change. Further, in industries experiencing talent scarcity or where there’s heightened competition to attract in-demand talent pools, culture becomes a critical source of advantage.
Our research shows that this discipline translates into execution. Companies such as Xylem, Emerson, and Globus Medical made culture visible through integration outcomes, achieving early synergies and strong post‑close performance. This reinforces broader evidence that effective cultural management materially increases the likelihood of value realization.
M&A does not create uncommon growth by default. Even well-conceived deals fall short when leadership treats them as financial events followed by cleanup.
The success of M&A transactions hinge on deliberate choices by leadership: what the combined business stands for, how it operates, and what customers and employees should experience. When those decisions are made early and executed consistently, M&A becomes more than a transaction. It becomes a platform for uncommon growth.
To find out more about how to realize the real potential behind mergers, acquisitions and spin-offs, visit our M&A growth acceleration hub.
Chinese Brands Going Global: Five Strategic Shifts to Unleash Growth
As Chinese brands expand into the global market, they must move from exporting products to building brands and shaping consumer trends to drive uncommon growth with lasting competitiveness.
With the global talent dividend, fast-evolving AI technologies, and reshaping of consumer journeys, Chinese brands have entered a period of accelerated growth on the global stage. Companies are moving beyond simply “going out” in geographic terms and into a phase of “going in”—deep local embedding—where China’s manufacturing strengths are integrated with the ambition to build world-class brands.
As a result of our experience helping Chinese brands develop overseas growth strategies, we’ve identified five strategic shifts critical for success.
1. From “Channel Push” to “Brand Pull”
Chinese companies excel at pushing products efficiently into channels through their mature supply chains and precise e-commerce operations. However, over-reliance on channel push can turn the brand into an “invisible supplier,” weakening its identity and meaning that would resonate with end consumers.
In the next phase of global growth, Chinese brands are adopting a dual-engine model—protecting channel advantages while building brand strength. Consumers not only can buy the products that are accessible or affordable, but also want to buy, enabling more sustainable, long-term growth.
For instance, DJI established a clear, innovation-led brand identity early, standing for reliable, creator-friendly aerial imaging while operating a comprehensive distribution network. This helped it earn trust, mindshare, and premium positioning across major international markets.
2. From Product Function to “Differentiated Value
Chinese companies are strong at solving problems, but often less so at creating meaning. Many brands communicate primarily through functional narratives—features, specifications, and prices, pushing them into price-based, homogeneous competition. As a result, they fail to make a distinctive impression on local consumers’ minds.
To create meaningful values, brands must move beyond functional performance to define differentiated benefits by understanding different consumer segments and consumption scenarios. The goal is to shift from being seen as a substitute option or commodity to becoming a preferred or premium choice in the category.
As BYD expands into Europe, it complements channel execution with a clear sustainability-led brand promise, reinforced through brand campaigns and initiatives such as sustainability festivals and participation in major climate-focused events. These efforts help the brand build meaning and trust beyond functional vehicle attributes.
3. From Hero Product to Product Portfolio
A single successful product can ignite growth, but it can also limit expansion if the company gets ‘locked’ into one item. Brands should take a future-back approach early—designing hero products with a value proposition that supports long-term, sustainable growth. In this way, the hero product is not only a sales driver but also sets expectations for what the brand stands for.
From that center point, the brand can build a cross-category product matrix that offers solutions for diverse consumer needs. Only by building a tiered product portfolio can brands create a clear path to scale in global markets.
A good example is Xiaomi, which built global awareness through cost-effective smartphones but anchored its expansion in a consistent “tech enthusiast” identity—using that credibility to grow into a broad, tiered ecosystem spanning everyday smart-home appliances and devices as well as more advanced innovation bets such as robotics and electric vehicles.
4. From Platform Traffic to Omnichannel Experience
Many Chinese companies have become e-commerce experts that master the algorithms of platforms such as Amazon or Shopee. But this growth model contains a major risk: consumers may only remember buying something “on Amazon” while having no connection to the brand itself. These brands struggle to build meaningful brand equity, thus losing the ability to re-engage and retain customers throughout the full customer journey.
In the next phase of growth, brands must think beyond driving sales on e-commerce platforms and reimagine their digital storefront as a core brand-building base, and from there, create true omnichannel experiences. The strategic shift is from short-term acquisition to long-term customer engagement—building repeat purchase, advocacy, and a more defensible competitive position.
5. From Fragmented Voice to Consistent Messaging and Execution
As AI plays a larger role in discovery and evaluation, consistency across all touchpoints becomes crucial. AI and large language models scan internet-wide data to model brand perception: when official messaging, user reviews, and real experiences are highly consistent, the brand is given higher weighting and is more likely to be recommended; when messaging is fragmented or contradictory, it is treated as ‘noise.’
Brands today must be consistent inside and out, extending what they stand for across every touchpoint. Consistency over time builds credibility and improves conversion, retention, and reputation in the age of AI-driven recommendations.
The new era of globalization is not only about entering more markets; it is about elevating brand strength for uncommon growth. In more competitive environments, a brand’s staying power depends on whether it has real clarity, consistency, and customer preference—not only operational strength.
That staying power is built through:
Brand pull to complement channel strength
Differentiated value beyond product function
A future-back product portfolio rather than a single hero product
An omnichannel customer experience to reduce platform dependence
Consistent messaging and execution to build credibility in an AI-driven buying process
When Chinese enterprises extend their manufacturing capabilities into these five areas, they can move from exporting products to building brands—and shape global consumer trends with lasting competitiveness.
Beyond the Big Name: How to Choose a Strategy Partner for Uncommon Growth
The shift from optimization to transformation.
The consulting landscape is undergoing a fundamental shift. Historically, many of the relationships between an enterprise and a management consulting firm were anchored in efficiency. It was about “optimization”—squeezing more value out of existing assets, cutting costs, and refining legacy processes. However, in an era defined by volatility, shifting consumer expectations, and the rapid rise of generative AI, incrementalism is no longer a viable strategy.
Today’s market demands transformation, not just optimization. At Prophet, we were built specifically to bridge the gap between traditional management consulting and creative agencies—a gap that has only grown more significant as growth, digital, and brand strategies have become inseparable. As we have evolved our own capabilities, we have observed that while many firms are capable, few are “fit for purpose” in a world where the speed of change outpaces the speed of traditional strategy. This guide is designed to help leaders across functions identify the characteristics of a partner who doesn’t just solve immediate problems but unlocks long-term opportunities.
Shift 1: The Growth Mindset — Moving from Common to Uncommon
The most significant trap in modern strategy is “Common Growth.” Most firms rely heavily on historical data to predict future performance. This results in linear, mostly predictable outcomes that are easily replicated by your competitors. If everyone is looking at the same data through the same lens, everyone arrives at the same conclusion.
To break away from the pack, businesses must seek “Uncommon Growth.” This is growth that is:
Sustainable: Focused on building internal capabilities to ensure that it is a rolling thunder of moves rather than chasing one-off tactical wins.
Faster: Compressing the time between a raw insight and market execution, with strong strategy still in between.
Smarter: Utilizing advanced data and AI, combined with expertise, to identify hidden patterns that competitors miss.
More Human: Ensuring the strategy resonates emotionally with both employees and customers, especially in an increasingly AI-driven world.
More Actionable: Actively eliminating the “strategy-to-execution” gap.
The Litmus Test: Ask your prospective consulting partner: “How will this firm’s vision for our strategy make us fundamentally different and uniquely positioned, rather than just slightly better versions of our current selves?”
Shift 2: Proven Experience — The Intersection of Category and Corollary
A frequent question in the RFP process is: “Have you done this in my specific industry?” While industry depth is a baseline requirement, relying solely on industry experts often leads to “groupthink.”
True innovation usually happens at the intersection of category and corollary. Over our 30 years of global experience across industry categories, we’ve found that the solution to a retail challenge often resides in a healthcare model, or a CPG breakthrough that might be inspired by a tech platform’s user experience. Whether working within highly regulated sectors like financial services or navigating the complexities of companies grown through M&A or private equity, the best partners bring a “cross-category, cross-use case” perspective. They’ve seen how different industries solve similar problems and can adapt those lessons to your unique context.
The Litmus Test: Look for a firm that both understands your industry and can explain how a successful solution from a completely different sector might be adapted to solve your specific challenge (i.e., how does your hospitality experience influence my healthcare challenges I am trying to solve?).
Shift 3: Fluency in Business Strategy and Economics
A strategy that doesn’t move the P&L is just a dream. A partner must demonstrate a profound understanding of your business model’s unit economics from day one. There must be a balance between the “art” of brand building and the “science” of financial impact.
Consider our work with T-Mobile. The “Un-carrier” movement wasn’t just a marketing pivot or a clever slogan; it was a fundamental business model shift with a financial outcome. It changed the way customer lifetime value (CLV) and churn were calculated in the telecom industry. By building a rigorous business case for the C-suite and the Board, the strategy didn’t just win attention—it changed the EBITDA trajectory of the entire company, and in this case, the industry.
The Litmus Test: Evaluate whether the firm brings both creativity and data-driven economic rigor. Do they speak the language of the CFO as fluently as they speak the language of the CMO?
Shift 4: Speed to Impact — The Agile Strategy
The days of the six-month discovery phase are over. In today’s world, a half-year study is a death sentence for innovation. Clients now require “Speed to Impact” but with a strong strategic foundation.
Modern partners should work in sprints, delivering “Minimum Viable Product” (MVP) strategies that can be tested, measured, and iterated in real-time. This requires a robust ecosystem of capabilities and also a willingness to test, learn, modify, and scale quickly. For example, our AI Accelerator Network is a curated group of partnerships designed to help clients move from concept to market at breakneck speed and high quality.
The Litmus Test: Ask, “What is the shortest path to a ‘win’ that proves this strategy is working?” Check if they have the executional chops alongside the strategic chops to provide hands-on support in getting that idea to market.
Shift 5: Internal Socialization and Leadership Alignment
Even the most brilliant strategies fail due to internal friction. A consulting firm must be as skilled at managing stakeholders and organizational politics as it is at analyzing spreadsheets.
A true partner doesn’t just hand over a deck; they help you “sell” the strategy internally. They build it with you and key stakeholders. They create a narrative that the C-suite can rally behind, and that the frontline can actually execute. This requires a deep commitment to change management, at all levels, providing the tools and the storytelling necessary for the program’s long-term success.
The Litmus Test: Does the firm have a concrete plan for aligning your leadership team, or do they expect you to do that heavy lifting alone?
Shift 6: Cultural Fit — Working “With” You, Not “At” You
Finally, there is the “vibe” test. Some firms work “at” you—they deliver a finished product from a “black box” and disappear. Others work “with” you, becoming a seamless extension of your team and your organization.
Look for humility and pragmatism. Choose a firm that spends more time listening to your frontline employees and your customers than they do presenting its proprietary methodologies. A human-centered approach to consulting means respecting your company’s unique culture and values while pushing you to evolve.
The Litmus Test: During the pitch, do they ask curious, probing questions about your culture and past project successes and failures, or is the entire session a one-way presentation of their credentials?
Choosing a strategy partner is one of the most consequential decisions a leader can make. The “safest” choice — the biggest brand name — can be one that delivers “common” results. The best partner is the one that combines the rigor of business strategy with the imagination of a creative studio, all in service of delivering uncommon results.
Prophet’s 2025 Corporate Earnings summary with 2026 implications
Each year, we review corporate earnings reports from across regions, sectors, and sizes, distilling the learnings, strategies, guidance, and big bets into key themes for industry leaders. Giving a sense of what the last year might shape for the landscape ahead.
Which, with 331 S&P 500 companies citing “AI” during earnings calls conducted between December 15 and March 11, 2026—up from 241 in the same period last year—it’s no surprise that AI is taking up a lot of visible horizon.
Let’s get into it.
1. AI: From Building Block to Growth Engine
2025 saw unprecedented investments from those leading the AI charge. $400B+ of total AI-related capex spending from the “Magnificent 7” alone. But with major investment comes the need to prove ROI. Questions continue to circulate across industries: How long will this take? What will make the payoff worth it? Are we doing enough?
At Davos, Uber’s CEO Dara Khosrowshahi claimed many companies are “play-acting” with AI, saying the right words without fundamentally changing how their operations function. The difference is visible between companies that added AI to existing systems versus those that rebuilt their processes around it.
First came the infrastructure. The AI data center buildout created a rising tide for anyone positioned to supply it—right place, right time, mixed with speed to market and operational efficiency. Corning’s optical segment surged 35% to $6.3B. Celestica’s Connectivity & Cloud Solutions segment grew by 64%. Caterpillar’s power generation sales jumped 44% in Q4. Vertiv surpassed $10B, a 26% increase from 2024.
Other companies have been weaving AI into the core of how they work. Duolingo used AI to launch 148 new courses in under a year. Walmart’s “Trend-to-Product” engine tracks social trends and feeds concepts directly into sourcing, while its self-healing inventory system reroutes supply before shortages appear, saving $55M+. JPMorgan Chase and Mastercard embedded AI across trading, fraud detection, and transaction scoring to transform operational tools into revenue-driving capabilities. Uber rebuilt its customer-service systems from scratch, replacing rigid rules with clear goals for AI agents.
The fatigue of talking about AI for the sake of talking about it is real. But when you look at what companies are building? The advancements are remarkable—and company leaders expect those to compound with each passing year. The challenge is extracting value and turning towards AI as a growth driver versus an efficiency play.
2. The AI Talent Restructure
As for taking a stance on the role of AI in the workforce, some have gone all in: Duolingo’s CEO Luis von Ahn boldly declared the company “AI-first,” signaling a fundamental shift in how it hires and operates. Others have moved forward similarly, only without public statements. PepsiCo promised a “record year of productivity savings” in 2026 to fund growth without once mentioning AI in their Q4 earnings, even while Coca-Cola’s incoming CEO Henrique Braun made AI and digital a defining strategic priority.
To deliver these promises, companies have led colossal workforce restructurings. Intel, UPS, Amazon, and Verizon have all made cuts in the tens of thousands. Jack Dorsey’s Block laid off nearly half its staff, framing it as becoming a “smaller, faster, intelligence-native company,” an operating model reset.
But for the AI powerhouses, these major talent shifts aren’t merely downsizing. Companies are paying a premium for the talent that can push them ahead. Meta, OpenAI, Google, and xAI reportedly offered $20M+ equity awards—and in some cases $100M packages—to recruit elite AI researchers. Capability-building now means smaller teams, higher talent density, and a few highly leveraged technical leaders.
Culture has proven to be a driver of uncommon growth across all industries. As AI implementation continues, organizations that communicate clearly and tie AI to employee impact and values are seeing faster, more sustainable adoption.
3. Reinventing Toward Relevance
The ripple effects of AI and last year’s ‘Proceed with Caution’ economy pushed companies to reinvent. We noticed a few distinct flavors of reinvention in 2025: the pivot, the shed, and the path to platform.
The Pivot
Tesla halted Model S/X production to build Optimus robots. Lemonade is reinventing insurance offerings to incorporate new AI realities. Southwest made a massive bet by introducing bag fees, assigning seating, and removing its “never expire” flight credits.
The Shed
Some companies are aiming to get smaller and stronger in specific areas. Comcast spun off its cable networks and leaned on theme parks and Peacock deals for revenue. Meta officially shifted its narrative from “Metaverse” to “Superintelligence,” no longer promoting Reality Labs for VR. Siemens is spinning off their Healthineers business. Medtronic announced the spin-off of its $2.7B Diabetes business to simplify operations and double down on procedural medtech, where its cardiac ablation solutions surged nearly 30%.
The Path to Platform
The companies that chose to keep adding were betting on becoming something else entirely. Robinhood evolved from meme-stock brokerage to financial super app—prediction markets, retirement, credit cards, banking, managed portfolios—with revenue up 52% to $4.5B and platform assets up 68% to $324B. The New York Times hit nearly 13 million subscribers by bundling news, games, cooking, and sports into a contained ecosystem. JPMorgan Chase continued rewiring itself as an integrated platform, backed by an $18B technology budget and the operational deployment of agentic AI.
For others, reinvention meant short-term loss for long-term potential. UnitedHealth absorbed a $1.6B restructuring charge against a backdrop of genuine turbulence and still grew full-year revenues 12% to $447.6B. The restructuring wasn’t a retreat, but a bet on what comes next.
Whether getting lean or integrating more capabilities, the underlying question remains the same: where and when will our investments pay off? We’ll see if that question drives continued reinvention in 2026.
4. M&A Outlook / The R&D Arms Race
From a muted M&A environment in 2024, deal volume and deal value were both up in 2025. There were notable acquisitions—Alphabet acquired Wiz to enhance AI-powered cybersecurity across multi-cloud environments, Verizon added fiber infrastructure through its Frontier deal, Paramount won the long battle for the premium-priced Warner Bros. Discovery, Dick’s Sporting Goods acquired Foot Locker, and Pfizer’s acquisition of Metsara brought it into the GLP conversation.
But there’s more to the story. Only about 7% of total corporate cash spending went to M&A; the rest? R&D and capex. Companies that try to buy growth are still waiting for the payoff. PE firms like Carlyle and BlackRock had successful fundraising and financial performance, yet the market still struggled to deploy capital in an environment where ROI is difficult, and AI makes future earnings less predictable.
The companies that drove growth in 2025 built it themselves. Meta is moving to own the entire AI stack, reducing reliance on NVIDIA and investing heavily in AI commerce. Palantir’s U.S. commercial revenue grew 137% year-over-year, with AIP becoming a repeatable growth engine. CrowdStrike pushed R&D spending up 38% to launch Falcon AIDR, a full AI-native security platform.
In healthcare, Eli Lilly invested $55B in manufacturing to scale GLP-1 production far beyond current demand, partnering with NVIDIA on AI-driven drug discovery to compress R&D timelines. Hims & Hers invested in proprietary telehealth infrastructure to build direct-to-consumer health at scale, and AbbVie is building a neuroscience franchise intended to rival the scale of its immunology business. The M&A window may reopen as clarity returns, but 2025 made a strong case that in an AI-driven economy, growth can be driven organically.
5. Customer Obsession: Know who You’re Serving
Despite a resilient (but wobbly) economy in 2025, some consumers acted as if nothing stood in their way. Moody’s Analytics reported that the top 10% of households were responsible for nearly half of all consumer spending, validating Powell’s characterization of a “bifurcated economy.” The companies winning at the top are commanding premiums by delivering differentiated experiences, and those winning at the bottom are using AI to deliver more for less. The companies in the middle—the ones doing neither—are getting hollowed out.
Winning at a Higher Premium
Netflix closed 2025 with over 325 million paid subscribers, and with another premium price hike on the way, it’s proving that relentless investment in IP consumers care about makes for inelastic demand. Crocs’ Jibbitz charm revenue hit $271 million in 2024, with 3/4 buyers purchasing charms to personalize their Crocs, turning a one-time shoe sale into an ongoing relationship. Colgate is pushing into premium with its Optic White Pro Series, positioning at-home whitening as a credible alternative to professional treatments.
Winning the Value
Costco raised membership fees for the first time in years, and, with a 92% renewal rate, no one flinched. Its private-label, value-driven Kirkland Signature brand continued to grow faster than the total business. DoorDash expanded well beyond food delivery into grocery, retail, and convenience, only adding value to its household name.
Stuck in the Middle
Target’s stock fell 34%. The company is investing in store remodels and trying to compete, though still not affordable enough to win the price-conscious shopper and not differentiated enough to command loyalty at the top.
Being ‘stuck’ doesn’t mean it’s over. Starbucks pivoted back to its beginnings, putting customer experience first with a $1B investment in its ‘Coffeehouse Uplift’ initiative to shift perceptions of a once dreaded destination to again being the token ‘third place.’ Even as they constantly evolve, focusing on core customers will likely be a key theme in 2026.
A special thank you to: Editors: Hannah Anderson, Moira Allen; Research: Harry Ball, Fabienne Haase, Caitlin Shin, Gibson Campbell, Zoey Gendler, Sophie Kang
The AI conversations, reinventions, and innovations show no signs of stopping. And in this rapidly growing area of an already ever-evolving market, there’s never been more risk or opportunity for growth. Last year’s winners harnessed their own capabilities and reinvigorated their approach to drive uncommon growth—how companies respond in 2026 and beyond will determine whether they become an Uncommon Growth Company.
Uncommon Growth Leader: How to Lead with Creativity and Collaboration
Uncommon Growth Leaders is an article series featuring bold leaders driving faster, smarter, more sustainable, more human and more actionable growth — what we call uncommon growth.
Chiaki Nishino, President of Prophet, sat down with Michelle Froah, a global marketing and innovation leader, to explore the leadership traits needed to drive impact in a world that’s anything but ordinary. In a conversation packed with insight and real-world examples, Michelle opens up about challenging legacy thinking, co-creating across silos, and why slowing down can sometimes help you move faster.
In today’s high-pressure environment, there’s constant pressure to deliver growth. How do you push boundaries when it’s often easier or expected to do things the way they’ve always been done?
Michelle Froah: One of the most powerful skills I lean on is co-creative problem solving. It’s not about having all the answers, it’s about bringing together brilliant people from across the business, especially those who’ve been working in silos and building solutions together. When teams feel ownership and safety to challenge norms, innovation happens.
A great example is when I was working at CoverGirl. At the time, the “eyes” category — mascara, eyeshadow, eyeliner — was seen as a small piece of the business. But when we dug into the data, we found that eyes had higher velocity and margin than any other category. That insight reframed how we approached strategy and led to innovations like LashBlast, which ultimately elevated the entire brand. It was a team effort powered by data, creativity and cross-functional collaboration.
That’s a perfect example of disruptive thinking. What leadership trait do you rely on to drive that kind of disruptive change?
MF: Hands down: collaboration. It’s often called a “soft skill,” but in reality, it’s one of the most durable leadership capabilities. At ETS, we tackled a full transformation: business strategy, brand and innovation. But we couldn’t do it alone. ETS is a 75-year-old nonprofit with a deep research legacy, so we had to bring everyone along from researchers to business units, to functions including marketers. Only by co-creating together did we launch a new brand and strategy in under nine months.
People think rebranding is about logos and colors. It’s not. It’s about aligning everyone around a shared mission. When we unveiled the new brand, everyone walked out as a brand ambassador. That only happens when transformation is co-owned.
Sounds like leading change requires both vision and execution. How do you balance the two?
MF: You absolutely need both. When you set a bold vision, and then break it into tangible building blocks, you make big change feel possible and doable. Leaders need to set a future that feels bold, even a little scary, but also provide clear steps so teams see how to get there.
I’ve seen this in practice at both Samsung and ETS. At Samsung, we rebuilt customer trust after the Note7 crisis by directly engaging our most loyal customers and partnering our marketing with customer service, something that hadn’t been done before. At ETS, we ensured that transformation wasn’t just a marketing initiative, but something embedded across business units, research and operations.
In both cases, it was about setting a vision and then collaborating across silos to make it real.
How do you stay inspired to lead through all this complexity and pressure?
MF: Two things: First, I stay close to the work. I host working sessions, not just decision meetings. I want my teams to feel like we’re in it together not just presenting for my approval. It builds trust, encourages team development and gets better solutions faster.
Second, I look outside the walls of the organization. I stay active with groups like the ANA and The Marketing Society, sit on advisory boards and take the opportunity to mentor and be mentored.It keeps me curious, humble and open to ideas from completely different industries and perspectives.
Collaboration clearly plays a big role in your leadership style. How do you build a team culture that supports creativity and experimentation?
Michelle: You’ve got to embed it in the culture. It starts with accountability and investment in talent. At P&G, where I spent 18 years, 50% of your performance rating was based on results and the other 50% on organizational capability — how you developed your teams and others across the organization. That instilled in me a responsibility to grow talent that delivers outcomes, not just deliver outcomes.
So I always ensure that my teams have personal development objectives. Growth can mean deepening expertise or stepping into new, uncomfortable spaces to expand capabilities. Either way, it forces collaboration, mentoring and continuous learning.
What’s been one of your biggest leadership challenges to drive growth?
MF: The biggest challenge is often inertia, the resistance to new ways of thinking. But if you can tap into people’s sense of purpose and show them the value they’re creating, you turn skeptics into lifelong partners.
Transformation is hard and can invoke skepticism. At Samsung, during the Note 7 crisis, we had to rebuild trust. And we did this by engaging our most loyal customers and working hand-in-hand with the customer service team to create new experiences like white-glove service. It pushed us to innovate in ways we hadn’t before.
At ETS, launching a new business unit and workforce solution was an investment that required significant buy in across the organization. But when you tap into people’s desire to make a difference, you gain an opportunity to build relationships that may turn into lifelong partnerships.
Final question: What’s the anchor point of your leadership — something you rely on no matter where you’ve worked?
MF: I’m naturally driven, fast-paced and not afraid of change or risk. One of my favorite poems is The Road Not Taken, because I’ve always chosen the less-traveled path.
But I’ve learned that sometimes slowing down helps you go faster. When you give others time to catch up emotionally and strategically you get stronger buy-in, better ideas and faster momentum in the long run.
So yes, I still love a good sprint. But I now know when to pause and bring people along. That’s how you turn a big idea into a movement.
Michelle Froah is an accomplished global executive recognized for driving business transformation, modernizing brands, and leading digital and AI-enabled growth across complex global organizations. She most recently served as Global Chief Marketing & Innovation Officer and SVP of Corporate Solutions at ETS, where she helped return the company to profitable performance and built new growth pathways through enterprise innovation, AI strategy and the launch of Futurenav, a workforce solutions venture.
Across senior roles at MetLife, Samsung, Kimberly-Clark, and Procter & Gamble, Michelle has shaped global brands, guided digital transformation, strengthened customer-centric strategy, and scaled organizational capability across diverse, regulated, and high-growth industries. Her leadership has been recognized with industry honors including AdWeek’s AI Trailblazer Power 100, Campaign’s 40 Over 40, Business Insider’s CMO to Watch and multiple Brand Innovators Top 100 Women distinctions.
This conversation is part of our ongoing Uncommon Growth series, where we explore what’s possible when senior leadership aligns not just on strategy, but on how to achieve uncommon growth. Personify Health’s journey — powered by a strong CEO-CMO partnership, a new brand and bold thinking — offers a blueprint for driving performance through clarity, trust and creative disruption.
We often see companies consistently outperform because they share one defining trait: they operate with clarity. This allows them to turn insights into sharp strategies, distinctive experiences and to align their cultures behind a shared direction.
Of all the factors that fuel business growth, clarity is one of the most critical—and sometimes the most overlooked. Without clarity, blind spots multiply, decisions falter and growth slows.
When Prophet published Uncommon Growth for Uncommon Times, one message stood out: the winners don’t rely on slogans; they build purposeful systems that clearly connect strategy, people and performance.
Clarity is about having the right lens to understand your key issues. Below are four examples of how we partnered with leadership teams to help them stop guessing and pursue a clear plan towards growth.
Finding Clarity Through Customer Insights
Clarity starts with understanding customers. Without meaningful insights, executives often struggle to prioritize effectively and pick the best growth trajectory.
A leading consumer goods company was faced with a fragmented market and uncertainty about future growth. We delivered clarity by building a demand landscape that combined research, segmentation and cultural trends analysis. This pinpointed distinct growth territories and aligned leadership on where to play, and how to win.
Similarly, a premium pet nutrition brand needed to scale without losing authenticity. By uncovering the motivations behind pet owner choices and mapping the most valuable demand spaces, we created a unified strategy that guided innovation, channel priorities and experience design.
Through our work, their leadership team was able to understand the real story of what was happening in their markets and to develop clear, actionable insights that turned complexity into confidence.
Making Innovation Clear—and Profitable
For many leaders, the real challenge isn’t sparking innovation; it’s sustaining it and proving its value. Clarity means building a system where creativity consistently translates into measurable business success.
A global industrial manufacturer wanted to move beyond incremental product development and create a durable source of differentiation. We helped design an innovation engine that identified unmet customer needs, defined a portfolio of growth bets and established a framework for testing and scaling ideas.
By embedding innovation as a core capability, the organization was able to fund, build and launch new offers faster.
Clarity in Brand Portfolios: Making Every Brand Work Harder
When categories blur and portfolios expand, it can lead to a lack of awareness of which brands create real value and for whom. Without that knowledge, investments scatter and experiences fragment.
We helped a hospitality group overcome brand overlap and inconsistent customer experiences by defining high-value guest segments, clarifying brand roles and creating a loyalty roadmap that guided investment and experience design across the portfolio.
In another case, a global consumer company needed sharper focus for its growing portfolio. Our demand-space analysis defined each brand’s role and target, providing a roadmap that unified marketing, innovation and commercial teams.
Clarity in Culture: Connecting Organizations
Behind every successful transformation sits one constant: clarity on the behaviors and beliefs that unite people behind a common culture.
A fast-growing pharmaceutical services organization was expanding globally and needed to preserve its entrepreneurial energy while scaling effectively. Prophet worked with the leadership team to codify a culture framework that defined the values, behaviors and rituals connecting employees to the company’s purpose.
Through co-creation and leadership activation, these behaviors were embedded into daily work—turning culture into a catalyst for performance and growth.
Despite ongoing disruption, the CEO agenda is sharper than ever. Leaders are zeroing in on several priorities: understanding customers in richer ways, embedding innovation into everyday work, maximizing brand value and building cultures that move with intent.
Our experience shows clarity isn’t just a leadership skill; it’s a deeply connected growth system that turns ambition into sustained performance.
To find out more about how to take the guesswork out of your strategic leadership, please get in touch.
From Programs to Platforms: Modernizing Loyalty to Unlock Growth
How to design loyalty programs as growth platforms that retain customers, attract new ones, and maximize value.
In a time of economic uncertainty, ruthless competition and ongoing transformation, companies of all types look to loyalty programs to protect share and fuel growth. The most effective programs no longer act like isolated “earn-and-burn” schemes. They operate as integrated platforms and fully connected ecosystems that deepen emotional ties with customers, unlock richer data, and open new revenue streams
As history shows, loyalty programs are not “set-and-forget” endeavors. Ongoing investment and continuous improvement are required to stand out from the pack and maximize bottom-line impact over the long term. But recent research and market experience show that companies can modernize and optimize their loyalty programs by applying the principles of platform businesses (e.g., connecting consumers with richer offerings, leveraging network effects) to generate uncommon growth.
The Evolution of Loyalty Programs: From Purchase-Driven Schemes to Differentiating Experiences
In the early days, loyalty programs were narrow in scope and operated in simple, straightforward fashion: customers earned points for purchases and then redeemed those points for discounts or special offers. Typically, the goal was to drive repeat purchases though monetary rewards and recognition. These programs worked well enough that they became standard in some industries, though there was a common downside to their transactional approach: increased pressure on margins that sometimes sparked a race to the bottom.
Today, loyalty programs have become commoditized because of intense competition and the dominance of co-branded credit cards. There is an entire sub-culture of “points experts” and consumers who make a hobby of maximizing their rewards. Rising customer expectations for rewards and benefits make any modifications to loyalty programs a sensitive matter.
Over time, forward-looking brands began to see loyalty as a platform for growth, not just a retention tactic. Today, the most effective programs function like connected ecosystems, going beyond the foundation of rewards and recognition to build communities, foster long-term engagement and even attract new customers. Instead of rigid tiers of rewards, benefits are more flexible and can be customized to customer needs. Most recently, paid membership models have added another dimension of opportunity for deeper engagement and differentiation.
The big insight is that emotional loyalty — built through connection, community, and relevance — is more powerful and sustainable than more traditional approaches focused exclusively on transactional rewards. Though they can be difficult to create, emotional connections turn loyalty programs from marketing cost centers into drivers of scalable growth and multipliers of brand value.
A Brief History of Loyalty Programs
The first loyalty programs date back centuries and trading stamp programs were common in the early 1900s. But the modern era began in the early 1980s, when major airlines started frequent flier programs.
Though the benefits of loyalty programs are self-evident to executives in many sectors, research reveals the full depth and breadth of the value proposition.
Increased Revenue and Profitability
At a time when marketers are being asked to simultaneously reduce overall spend and grow revenue, loyalty programs help them do more with less. According to Antavo’s annual Global Customer Loyalty Report, 83% of loyalty program owners report positive ROI with an average return on investment of 5.2x.
Other research shows that increasing customer retention rates by just 5% can boost profits by 25% to 95%. Retained customers are also more likely to try new products and spend more than new customers because they are familiar with the brand. Given pervasive economic uncertainty, CMOs can’t afford to overlook such huge potential upside.
Well-designed loyalty programs offer a clear incentive to choose one brand over another. Programs oriented around exclusive experiences (e.g., early product drops, dedicated store hours, members-only perks, access to exclusive restaurants) can attract even the most demanding (and highest net-worth) customers. Further, they can drive word-of-mouth referrals by encouraging loyal customers to share the program with others.
The ROI of loyalty programs should also account for customer lifetime value (CLV) and reduced churn, which are especially important in times of cautious consumer spending. One study found that loyal customers spend more than 30% more and that emotional connections to brands can lead to a CLV that is more than 300% higher.
Data as Differentiator
Modern loyalty programs generate rich, first-party data about customer behavior, preferences and intent that power more relevant offers and richer customer journeys from day one. This is perhaps the most valuable information a company can get, particularly in the post-cookie world.
Further, the insights and data assets produced by loyalty programs are especially important for companies that are not digital natives but want to build or adopt elements of platform businesses. No longer just for tech companies, digital platforms provide visibility across the customer journey, enabling the company to watch customers make choices, use what they acquire and interact with partners.
The insights companies generate at every interaction offer opportunities for companies to add value. Loyalty data can also be used for strategic purposes, informing decisions about product development, service design, transformation initiatives, and even M&A strategy.
The New Era: Loyalty as a Platform
Treating loyalty programs as a platform lets companies:
Own customer relationships and data
Drive consistent engagement across channels
Experiment with monetization, personalization and service delivery
Build long-term differentiation, not just short-term reward loops
Winning With Modernized Loyalty Strategies
So, what does it take to be able to leverage loyalty programs as platforms for growth? And what leading practices can firms embrace to optimize the impact of their loyalty programs? In our market experience, we’ve identified a few attributes that characterize the most successful strategies.
Integration and personalization are the keys to creating engaging experiences across channels and for making loyalty programs essential vehicles for content, community, gamification, and ongoing interaction, not just transactions. They can even lead to major business model enhancements. And they are required for any firm that wants to develop paid loyalty options, with customers purchasing direct access to enhanced services (e.g., free delivery, members-only offers) or exclusive status tiers.
Fully Integrated and Data-driven:
First and foremost, loyalty strategies must be fully embedded in all interactions, including digital and physical environments and with every part of the organization (e.g., sales, service, billing). Modernized loyalty programs avoid restricting offerings to a card, app, or location. Such cross-platform and omni-channel connectivity has emerged as a leading practice.
The data generated by loyalty programs can — and must — be operationalized to personalize the entire customer journey in line with individual preferences. For example, Sephora analyzes purchase history and applies AI tools to recommend products and personalize offers for members of its Beauty Insider program. The results are impressive:
A 30% increase in customer engagement via personalized offers
3x higher annual spend among top members
15-25% higher annual revenue from active users
Purposefully Engaging
In fashion and apparel, the emphasis has shifted from solely monetary driven (e.g., points) to meaningful engagement around passion points. The North Face has advanced its loyalty program, XPLR Pass, by connecting rewards to outdoor exploration, sustainability, and social connection. By emphasizing community, shared values, and experience, the company has embedded the brand more deeply into customers’ lifestyles.
Similarly, H&M’s membership program rewards recycling and sustainable choices, with direct alignment between its loyalty strategy and ESG goals. The result? More than 120 million members across 26 markets now contribute 35% of overall revenues, with Plus members spending 3x more than non-members.
Gamified and Fun
Giving customers extra reasons to engage helps foster growth. KFC enhanced its loyalty program with a gamified arcade offering spin-to-win features and in-app challenges. This content and entertainment hub led to a 53% increase in app downloads and a 40% rise in reward redemptions. Same-store sales jumped 12% thanks to 25% of customers increasing their visit frequency.
High-value and Revenue-generating
CMOs should ensure they measure the effectiveness of loyalty programs based on tangible commercial metrics. That may be especially important for B2B organizations, given that there’s a common misconception that loyalty programs are largely for B2C industries. Miele’s B2B Dealer Loyalty Program features tiers based on sales volume and has moved the needle on critical metrics including 19% sales growth and a 62% rise in average appliances sold per order.
Many prominent tech companies offer expert training, advanced technical support, networking opportunities, referral bonuses, and marketing support to their most loyal corporate customers. The most effective of these programs have seen engagement and customer retention rise by 40%, as well as 10%-20% gains in annual revenue.
Loyalty programs are proven drivers of customer engagement, retention and growth. As important as those benefits are, the rich data and insights they provide are strategically invaluable. Modernized programs aren’t just about keeping the customers you have, they’re a strategic way to attract the customers you want and drive growth and stronger bottom-line performance, even amid economic uncertainty.
But just as customers are always looking for more value, loyalty programs must be designed and managed to foster ongoing innovation and ever-richer value propositions. Like any powerful growth drivers, loyalty programs must be By measuring and refining their loyalty programs over time, all types of firms can strengthen their existing relationship and build new ones, even as customer expectations for value continually rise.